Tax Moves To Make Before The End Of 2026
In this episode, Dr. Chris Mullis, PhD, CFP® explains why the most profitable hour you spend all year happens before December 31st through proactive year-end tax planning. We also unpack the hidden catches behind zero-dollar premium Medicare Advantage sales pitches, revealing why dropping your Medigap policy could create a costly, irreversible healthcare trap. Finally, we peer 15 million light-years into deep space to see how infrared views of the Southern Pinwheel Galaxy illustrate how to see past temporary market noise and keep your financial future bright.
Retirement Big Picture
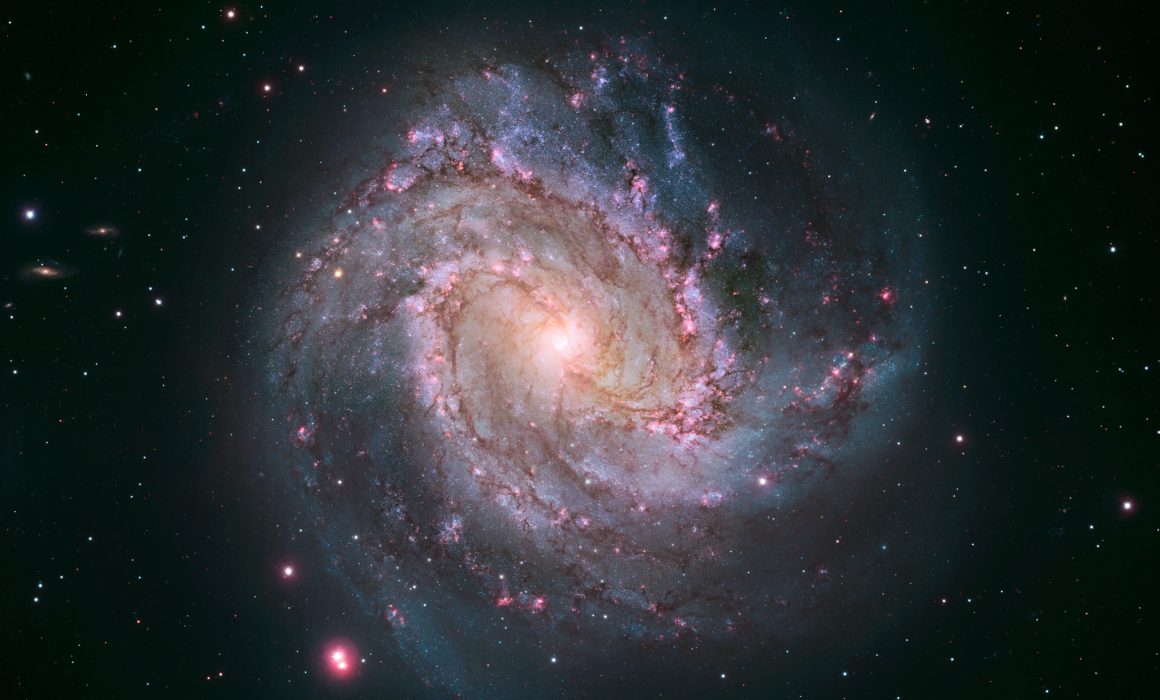
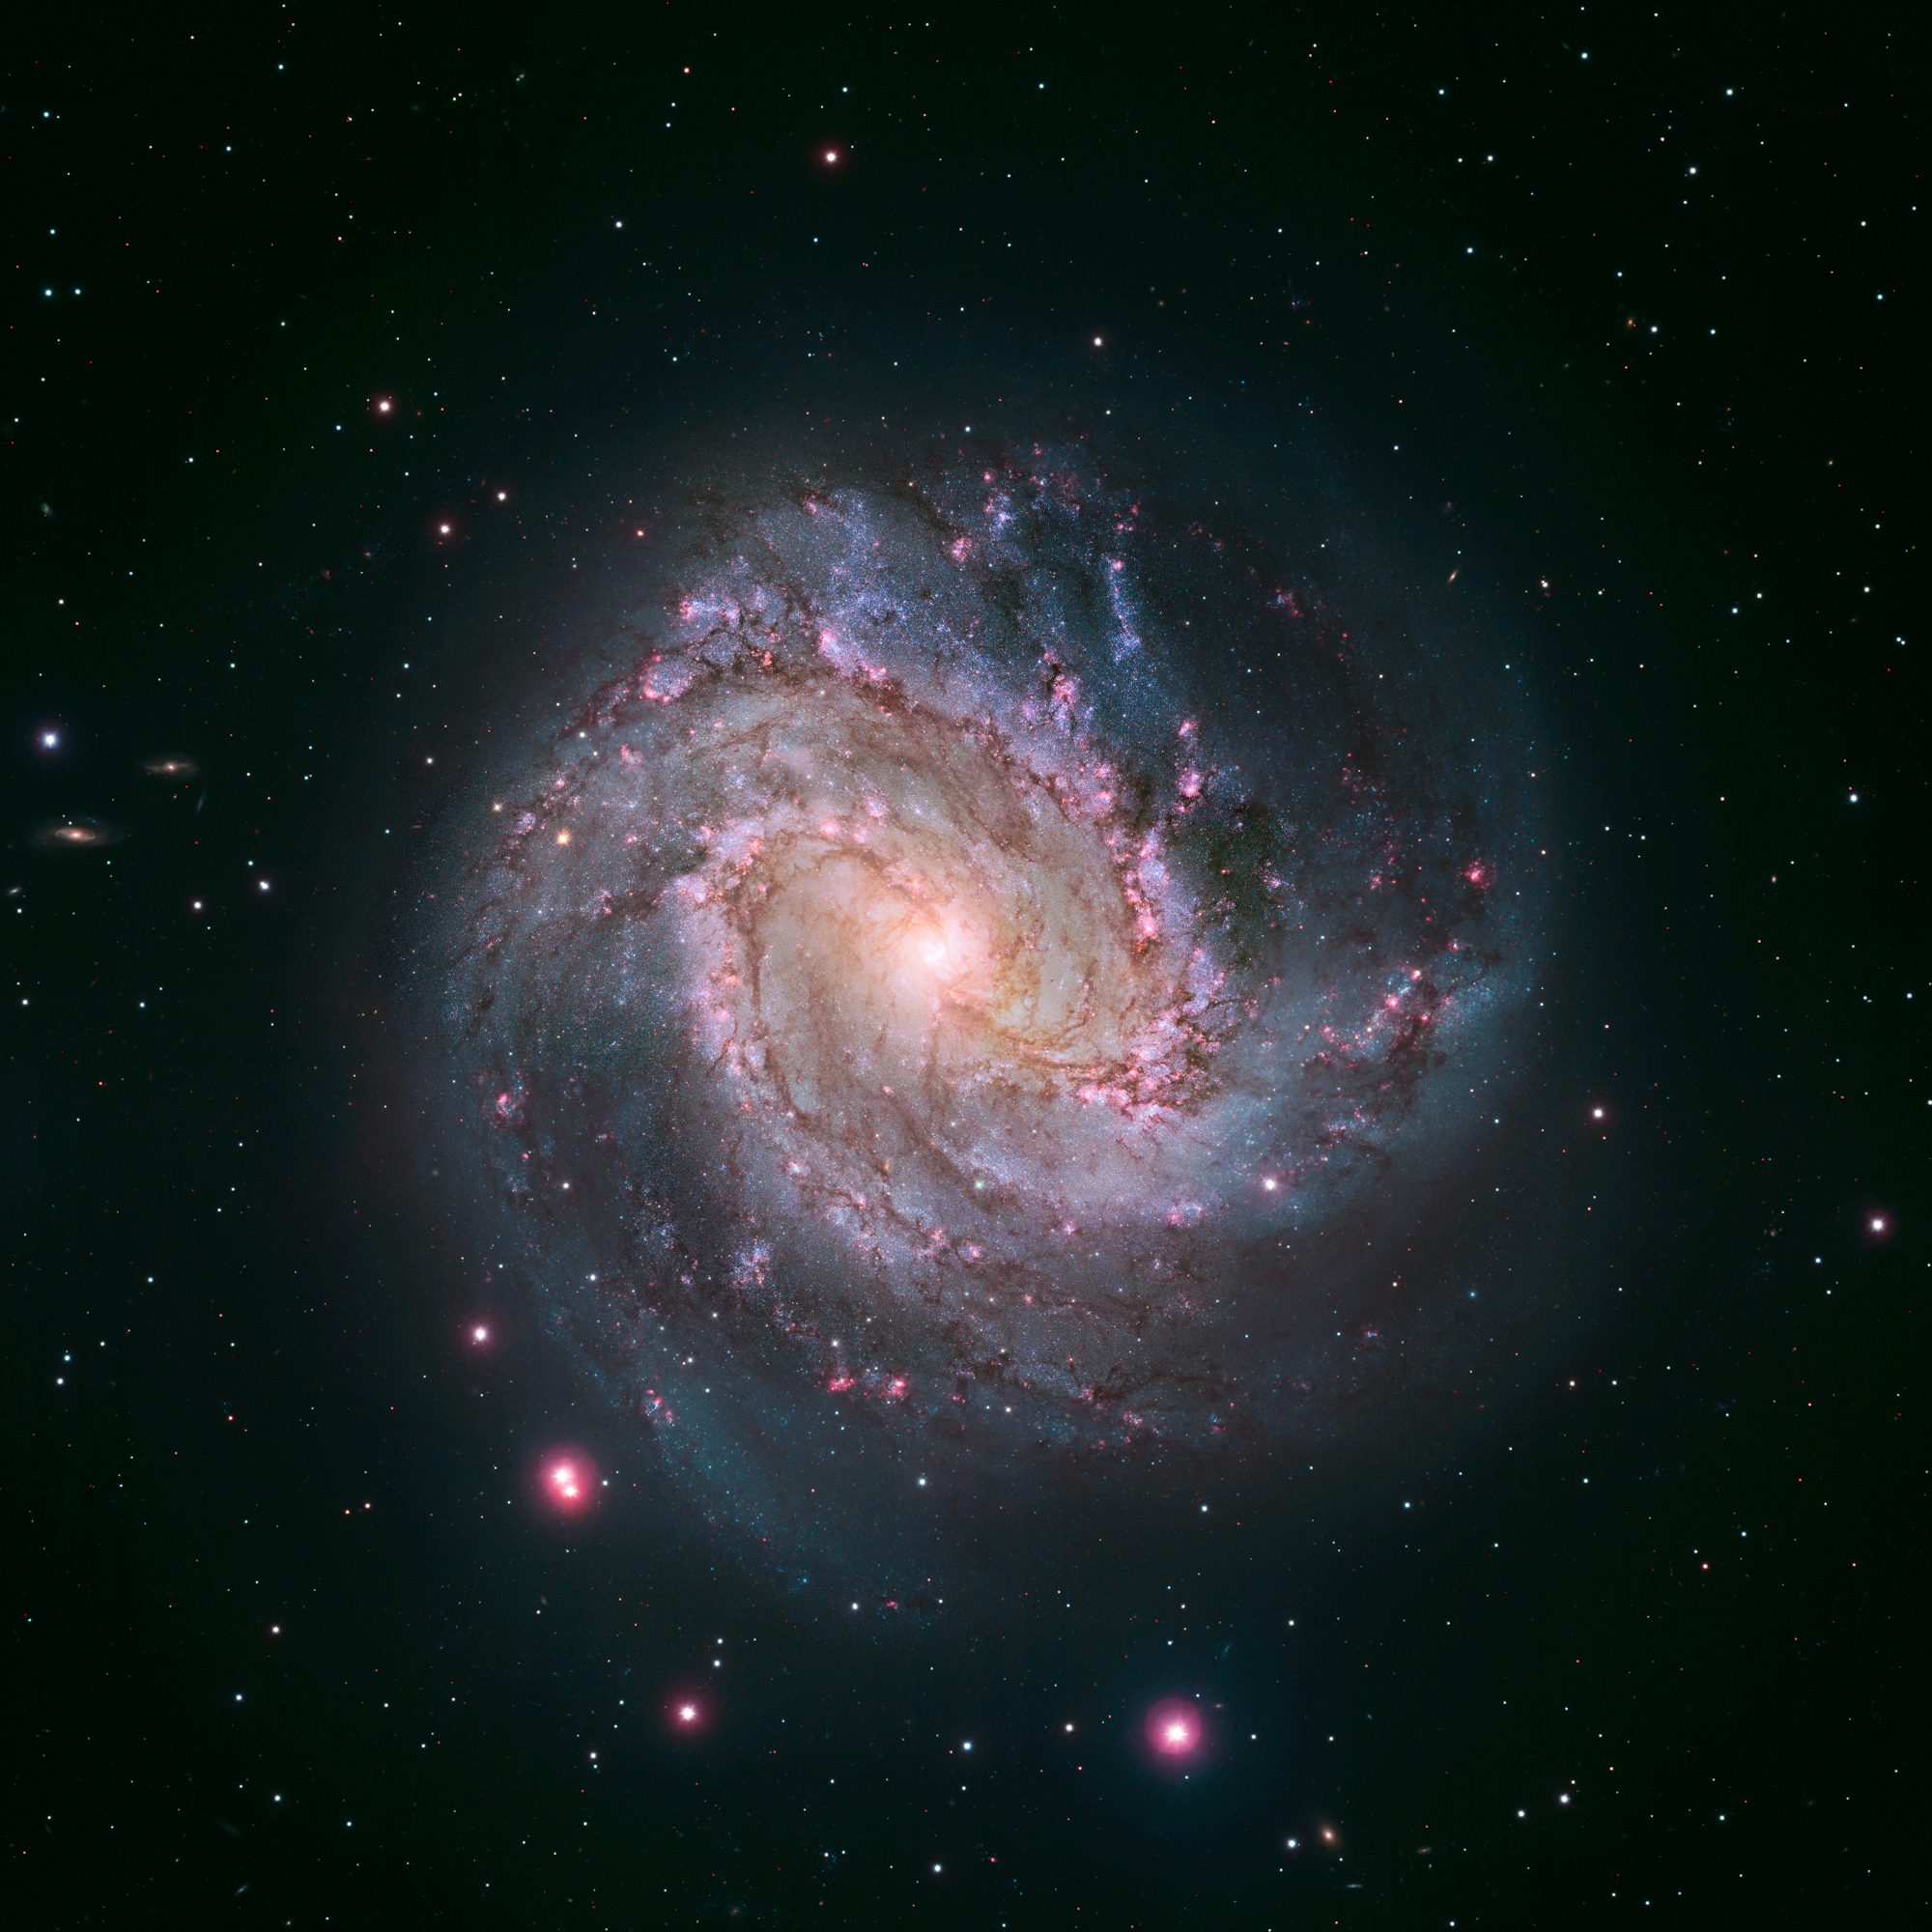
Messier 83, the Southern Pinwheel Galaxy, is a grand barred spiral galaxy situated 15 million light-years away in the constellation Hydra, featuring sweeping spiral arms and thick dust lanes. While dense interstellar dust obscures optical views of its core, the James Webb Space Telescope’s infrared vision pierces through the barrier to reveal intricate webs of gas and polycyclic aromatic hydrocarbon dust. The resulting imagery exposes a magnificent double nuclear ring at the core, fueling an intense circumnuclear starburst engine that continuously generates vibrant new star clusters.
Image Credit: NASA, ESA, and the Hubble Heritage Team (STScI/AURA)
Sign Up for The Launch
The Launch is a weekly email from Dr. Chris and his team. It’s full of retirement tips, news, listener questions & more, straight from us to your inbox. Get smarter about retirement in just 5 minutes every week. Let’s go!
Episode Resources
Episode Transcript
Introduction
Dr. Chris Mullis, PhD, CFP®: Most people think tax planning happens in April when you file your return, but by then the scoreboard is completely locked and you’re simply reporting history. What if the most profitable hour you spend all year happens right now, before December 31st, while you still hold all the cards?
Are you go for launch?
NASA: 3, 2, 1, 0 and lift off. Lift fell Americans return to space as discovery clears the tower.
Dr. Chris Mullis, PhD, CFP®: Welcome back to Retirement Isn’t Rocket Science, the show dedicated to taking the complexity out of your personal finances so you can worry less and retire more. I’m your host, Dr. Chris Mullis. I spent my first career as an astrophysicist using NASA’s space telescopes and the largest telescopes on Earth to map the outer edges of the universe.
Today, as a certified financial planner and retirement firm owner with 21 years of experience, I help you navigate your financial frontiers to lower your taxes, strengthen your portfolio, and give you the confidence to spend more. If you’re looking for professional help in your money journey, please visit retirednorth.com to learn if my team at North Star Capital Advisors is a good fit for your unique needs.
Episode 30 begins now.
In today’s show, is your year-end strategy defusing a million-dollar tax bomb or inadvertently triggering stealth taxes? And is trading your Medigap policy for a zero-dollar premium Medicare Advantage plan a brilliant money-saving move, or are you accidentally launching your healthcare into a one-way financial trap?
And looking out deep, unlocking the cosmic engine, what Messier 83 teaches us about clear vision, stellar growth, and long-term trajectory
Retirement Briefing Room
Dr. Chris Mullis, PhD, CFP®: Welcome to the Retirement Briefing Room. This is where we pull up the blueprint on your financial life, focus on what actually works, and map out clear, actionable steps for your retirement mission. As we progress through the final quarter of the year, we enter what financial planners like myself call the end-of-year tax planning season.
Now, many people assume tax planning is something we do in April when you file your return. But by the time April rolls around, you aren’t planning, you’re simply reporting history. Real proactive tax planning happens throughout the year and especially right now, before the stroke of midnight
on December thirty-first. Let’s break down the whats, whens, and whys of year-end planning. The what is all about taking deliberate, controlled actions to manage your marginal tax brackets, fulfill mandatory distribution rules, optimize charitable giving, and prevent costly penalties.
The when is about the tight window between October and December thirty-first. And the why is simple. Taxes represent the single largest expense you will face in retirement. However, as diligent savers, you possess a massive structural advantage over the IRS. You have a multi-decade horizon, and specifically, during the golden gap years, that’s the period between when you stop working and when Social Security or required minimum distributions begin, you have unprecedented control over your taxable income
Today I’m sharing how we navigate the season at my retirement and tax planning firm. Let’s start with a unifying principle. Year-end tax planning isn’t about over-engineering your entire wealth strategy. It is about sanding off the rough edges of your tax bill and avoiding unforced errors before hard calendar deadlines expire
I like to frame this as year-end planning around paying taxes on your terms, not the IRS’s. One of the biggest risks retirees face is the RMD bomb. That’s the required minimum distribution bomb. Having a million dollars or more accumulating in a pre-tax traditional IRA, only to be hit by massive forced taxable distributions in your mid-seventies.
Rather than waiting for the IRS to dictate your tax bracket, at Northstar Capital Advisors, we advocate executing targeted annual partial Roth conversions. By converting smaller amounts, say fifty thousand dollars at the end of consecutive tax years, you fill up lower tax brackets today, move money into a tax-free bucket for life, and diffuse future RMD spikes.
We operationalize this through our fall planning meetings. In October and November, our team finalizes our clients’ tax forecast. We use a guided discovery process called locking in your tax rate. If a client retired mid-year and finds themself in an unusually low ten or twelve percent marginal bracket, we’ll ask, “Your effective tax rate is extraordinarily low this year.
How much income do you want to lock in at this bracket to protect your future self?” We then execute precise Roth conversions, paying taxes out of cash reserves wherever possible, and locking in guaranteed historically low tax rates. However, executing year-end Roth conversions isn’t as simple as blindly converting money to the top of a bracket.
You have to watch out for stealth taxes. Extra income recognized at year-end can create unintended ripples across your financial plan. For instance, crossing specific income thresholds can trigger Medicare IRMAA surcharges two years down the road. They can levy a three point eight percent net investment income tax on your investments or wipe out Affordable Care Act health insurance subsidies.
Let me give you a real-world example. I’m working with a lovely client family where recognizing just one dollar in taxable income for twenty twenty-six will push them over the ACA cliff and cost them an additional twenty-seven thousand dollars in extra health insurance costs.
It pays to have a tax forecast that shines a light on costly pitfalls like this. Another great real-world example. During fall planning with a client couple who had sold real estate earlier this year, their routine plan was to draw IRA funds up to the top of the twelve percent bracket.
But because the property sale pushed their income higher, continuing IRA draws would have triggered severe ACA health insurance subsidy losses. We froze further IRA distributions for the year, balancing tax bracket management with healthcare costs. Another powerful reason to manage your tax brackets early in retirement is the surviving spouse tax trap.
And we took a close look at this during our fall planning this year, where we stress test our clients’ financial plans for the unfortunate loss of their partner. How would that look in their financial plan? How would income change? How would expenses change?
And how would taxes change? Imagine a married couple enjoying the spacious twelve or twenty-two percent joint tax brackets. If one spouse passes away, the surviving spouse must eventually file as a single filer. Single tax brackets are compressed to half the width of joint brackets, meaning the same income can instantly jump from a twelve percent tax bracket into a twenty-two percent or twenty-four percent bracket. By using strategic Roth conversions while both spouses are living and filing jointly, you lower future RMD requirements and protect the surviving spouse from single bracket compression later in life
now let me turn to charitable giving strategies. If you’re age 70 and a half or older, qualified charitable distributions or QCDs are one of the most effective tax moves available. We work with a retired couple who was donating one thousand dollars per month out of their checking account to charities.
Because they took the standard deduction, they received negligible tax benefit from those gifts while drawing taxable IRA distributions to fund their lifestyle. We restructured their strategy. They eliminated monthly checking account gifts and instead executed a single end-of-year QCD directly from their traditional IRA.
The result, they satisfied their charitable giving intent, fulfilled RMD requirements, reduced adjusted gross income dollar for dollar, and saved thousands in taxes. I want to offer two critical operational warnings for this year-end execution. First is the QCD check clearance trap. If you write a physical check from your IRA custodian to a charity for a QCD, again, that’s a qualified charitable distribution. If you write a check for a QCD in December, that transaction only counts for the current tax year if the charity actually cashes the check before December thirty-first. If the check sits on a desk until January second, you lose the tax benefit for the year.
My second insight is a smart fix for underpayment penalties. If you realized unexpected income late in the year or you missed a quarterly estimated tax payment, simply making an extra estimated payment in December will still leave you subject to IRS interest penalties for earlier quarters. However, the IRS treats federal tax withholdings from IRA distributions as if paid evenly throughout the entire year.
By taking a late December IRA distribution and directing up to one hundred percent of it towards federal withholdings, you retroactively satisfy IRS safe harbor rules and wipe out underpayment penalties instantly. If you are charitably inclined, I would encourage you to consider pairing your charitable strategy with capital gains management. For clients who want to give but aren’t yet 70 and a half, we utilize donor-advised funds or DAFs.
By bunching two or three years’ worth of charitable contributions into a single tax year using appreciated stock, you secure an immediate itemized deduction, avoid capital gains taxes, and grant gifts over time. We also highlight tax gain harvesting. If you are in a lower income year where taxable income puts you in the zero percent capital gains brackets.
That’s right, there is a zero percent capital gains bracket. If you have a low income year that puts you in this regime, deliberately selling appreciated assets before December thirty-first lets you step up your cost basis completely tax-free.
Finally, let’s not forget managing inherited IRAs under the ten-year rule. Rather than waiting until year number ten and facing a massive tax spike, year-end planning allows you to map out multi-year distributions, drawing down inherited accounts aggressively during lower earning gap years and pausing during higher earning years.
Before we conclude this segment, let me summarize the essential takeaways for your end-of-year tax mission. First, proactive tax planning happens before December thirty-first. Once the clock strikes midnight, your ability to alter the year’s tax trajectory disappears. Second, utilize gap years to perform precision Roth conversions and bracket filling.
But always model for stealth taxes like Medicare IRMAA surcharges and ACA subsidy phaseouts and cliffs. Third, optimize charitable giving through qualified charitable distributions if you are seventy and a half or over, ensuring checks are cashed before year-end. Or use a donor-advised fund for bunching to maximize deductions.
And fourth, review withholdings and safe harbor rules near year-end using late year IRA withholdings if necessary to avoid underpayment penalty traps. The beauty of retirement tax planning is that you don’t need to invent complex financial machinery. You simply need to execute the right moves before the calendar runs out.
Taking a couple hours each autumn to review your tax trajectory gives you total authority over your wealth, ensuring you pay every dollar you owe, but not a single penny more. Now let’s head over to Mission Control to answer your financial questions and get you retirement ready
Ask Mission Control
Welcome to Ask Mission Control. If you’ve got a retirement question you’d like us to answer on the show, head over to retirementisntrocketscience.com and click ask a question or call 704-234-6550 and record your audio question
This week’s question comes from John. He writes, “My wife and I are in our mid-70s, and we’ve been on original Medicare with a Medigap policy ever since we turned 65 over 10 years ago. It gives us great peace of mind, but lately, my phone has been ringing off the hook with sales pitches from Medicare Advantage.
The rep keeps pushing the fact that these Advantage plans have zero dollar monthly premiums and include dental and vision coverage, two big things that our Medigap plan doesn’t cover. On paper, trading our monthly Medigap premium for a zero dollar plan with extra perks sounds like a total no-brainer, but my gut tells me there’s rarely a free lunch in life.
What’s the catch here, Dr. Chris? Why shouldn’t we jump on these zero premium offers, or is there a hidden risk to dropping our Medigap coverage after all these years?” John, your gut instinct is operating a hundred percent accurately. In rocket science, when someone offers you a zero-dollar booster to your trajectory, you had better check what kind of navigation controls you’re handing over.
On paper, trading a monthly Medicare premium for a zero-dollar premium Medicare Advantage plan packed with routine dental and vision perks sounds like an easy win. But as retirement planners, we don’t just look at the shiny launch pad, we look at how your financial path handles severe atmospheric turbulence.
Here’s the big catch. You are trading complete freedom and fee predictability for a pay-as-you-go managed care model with strict boundaries. First, let’s talk about freedom of care.
With original Medicare paired with your Medigap policy, your medical flight plan is completely unrestricted. You can see any doctor, specialist, or hospital in the entire United States that accepts Medicare. That’s over ninety percent of physicians nationwide.
If you or your wife develops a complex condition and needs to visit top-tier specialists at the Mayo Clinic, MD Anderson, or the Cleveland Clinic, you can simply make an appointment and go. There are virtually no prior authorizations, no referrals, and no network barriers. If original Medicare deems care medically necessary, Medigap steps in and covers the bill.
Medicare Advantage, on the other hand, operates through private regional HMO or PPO networks. They require strict prior authorizations for specialized tests, surgeries, and cancer treatments. If the best oncologist or surgeon for your specific condition is out-of-network, your plan can deny coverage entirely or leave you with a massive out-of-pocket bill
Second, let’s look at the financial stress test. A zero dollar monthly premium looks great during healthy years, but Medicare Advantage relies on co-pays and co-insurance whenever you actually consume care. In a bad health year, out-of-pocket costs can reach federal limits as high as nine thousand two hundred and fifty dollars per year for in-network care.
With Medigap, you pay higher fixed premiums upfront, but your out-of-pocket costs during a medical crisis are essentially capped at minor deductibles. For diligent savers with a healthy portfolio, Medigap provides total cost predictability, serving as an indispensable shield for your wealth resilience.
Finally, there’s the most critical risk of all. We call it the one-way door rule. When you turned to sixty-five, federal law gave you a guaranteed right to buy a Medigap plan without any health questions. But after ten years, if you drop Medigap for Medicare Advantage now, jumping back isn’t so simple.
In most states, if you decide three years down the road that you dislike Advantage’s plan’s network restrictions and want your Medigap policy back, private insurers can subject you to medical underwriting. If you’ve developed high blood pressure, arthritis, or any chronic condition, they can charge exorbitant rates or deny your coverage entirely.
You could be permanently locked out of Medigap. Now, federal law does grant a one-time twelve-month trial right when you try Medicare Advantage for the first time, allowing you to return to Medigap within a year without underwriting. But why put your long-term health flexibility on the line for minor routine perks?
As a fee-only certified financial planner, my recommendation for clients with healthy nest eggs is to keep their Medigap shield intact and strong
If you want dental and vision coverage, don’t compromise your core health security. Simply purchase a standalone dental policy or pay those routine bills out of your cash flow. . Let me conclude by hitting the three key aspects.
Number one, provider freedom. Medigap offers nationwide doctor choice with no prior authorizations or delays, while Medicare Advantage limits you to local networks and private approvals. Number two, financial resilience. Medigap trades a predictable monthly premium for near zero out-of-pocket medical surprises, whereas Medicare Advantage can cost thousands in co-pays if illness strikes.
And number three, the one-way trap. Dropping Medigap after age sixty-five means passing medical underwriting if you ever wanna switch back later in life. John, thank you for submitting this really important question. I know it is relentless, the sales calls, the emails, , the letters pushing Medicare Advantage.
In both space exploration and retirement planning, trading long-term trajectory control for short-term fuel savings is rarely a winning formula. Keep your health shield strong, protect your freedom of choice, and enjoy the ride. Now, let’s look at what a spiral galaxy fifteen million light-years away can teach us about clarity, log-term growth, and navigating financial complexity
NASA: In Discovery Houston, we’ve got a good picture of Steve.
Retirement Big Picture
Dr. Chris Mullis, PhD, CFP®: Welcome to the Retirement Big Picture part of the show. This is where we look up and look out to enjoy and appreciate our amazing universe. Today, I actually hung out with some of my oldest astronomy friends, people I met when I was just 13 when I fell in love with astronomy.
Today, we’re setting our sights on one of the most magnificent barred spiral galaxies in the galactic neighborhood. That’s Messier 83, affectionately known as the Southern Pinwheel Galaxy. M83 was discovered way back in February of 1752 by a French astronomer observing from the Cape of Good Hope in South Africa.
It holds a special place in astronomical history as the very first galaxy beyond our local group to be cataloged. And let me just pause to explain that for a moment. The local group is a family of roughly fifty galaxies that is dominated by our own galaxy, the Milky Way, and the Andromeda Galaxy. So this is our inner family, our intergalactic family.
So M83 was the first galaxy to be discovered outside our inner family. Later, in February of 1781, the famous comet hunter Charles Messier added it as object number 83 in his iconic catalog, which is how we got its official name, Messier 83 or M83. Astronomers gave it the popular nickname Southern Pinwheel because of its sweeping spiral arms, rich dust lanes, and central star bar closely resembling the famous Pinwheel Galaxy M101 located in our northern skies.
M83 is located fifteen million light-years away in the constellation Hydra, the water snake. For our listeners in the United States, Hydra is indeed visible in the southern night sky during the spring months. However, because M83 sits fairly low on the horizon when observed from the northern latitudes, finding it requires a bit of patience.
For professional astronomers operating ground-based observatories, M83 is an absolute goldmine. Radio astronomers using the Very Large Array, the VLA in New Mexico, have tracked radio signals from six historical supernovae exploding in M83 over the past century.
That makes M83 the most prolific supernova factory anywhere nearby. These multi-wavelength ground observations allow scientists to measure how supernova remnants fade over decades, proving that ground-based telescopes remain essential partners to space observatories.
And speaking of those space-borne telescopes, space observatories have added incredible depth to our understanding. NASA’s Hubble Space Telescope captured crisp optical views of its star clusters, resolving individual stellar nurseries across this galaxy’s fifty-five thousand light-year span. While Chandra’s X-ray observatory searched for high-energy radiation from dying stars.
And more recently, NASA’s flagship James Webb Space Telescope turned its powerful infrared eyes towards M83. And what did Webb reveal? Invisible light. Dense patches of interstellar dust obscure the galaxy’s inner dynamics. But with JWST’s infrared vision, it pierces right through that dust. Webb’s images highlight intricate webs of gas, polycyclic aromatic hydrocarbon dust. Say that three times. And a stunning double nuclear ring at the center. This reveals an intense circumnuclear starburst, an internal engine churning out vibrant new star clusters at a remarkable pace.
Just as M83 relies on an internal starburst engine to power new stellar growth despite thick cosmic dust, a successful retirement relies on a well-designed financial engine. When you’ve worked hard to build your nest egg, short-term market noise or tax complexity can sometimes feel like patchy interstellar dust blocking your big view.
But when you look through the right lenses with a trusted advisor, you can see past the temporary noise, protect your wealth, and keep your financial trajectory clear and bright You’ll find a majestic image of M83 that combines space and ground-based imaging in this week’s newsletter called The Launch.
You can sign up for The Launch at retirementisntrocketscience.com.
Conclusion & Action Items
Dr. Chris Mullis, PhD, CFP®: Before you hit the ground running, here’s your retirement mission checklist. These are the important actions you should tackle this week to make your retirement even better. Number one, calculate your remaining tax bracket capacity before December thirty-first. That means gathering up your year-to-date statements, pensions, capital gains, and interest income to determine how much room remains in your current marginal tax bracket for targeted Roth conversions or top-off IRA withdrawals.
Number two, audit your charitable giving strategy. If you’re age seventy and a half or older, shift charitable donations out of your personal checking account and execute direct qualified charitable distributions from your IRA. If issuing physical QCD checks in Q four, please confirm with the charity that they will be depositing and clearing your check prior to December thirty-first.
And number three, perform a safe harbor withholdings and stealth tax verification. That means review your total tax withholdings against IRS safe harbor guidelines to ensure you avoid underpayment penalties. Simultaneously, run a multi-year projection to verify that end-of-year income moves won’t inadvertently trigger Medicare surcharges or aCA subsidy cliffs. Thank you so much for listening, and please share this with someone who might benefit from learning from the podcast. This is Dr. Chris reminding you, you are both the commander and the pilot of your amazing retirement mission.
Take control of your trajectory today to worry less, and retire more, because with thoughtful planning that includes end-of-year tax planning, retirement isn’t rocket science
Credits
Dr. Chris Mullis, PhD, CFP®: We thank the National Aeronautics and Space Administration for providing the radio communications between the space shuttle astronauts and the flight controllers.
Disclaimer
This show is for informational and entertainment purposes only. It is not specific tax, legal, or investment advice. Before considering acting on anything you hear in this show, first consult your own tax, legal, or financial advisor