Flight Plan for Your 50s and 60s: Navigating Retirement’s Forgotten Age Milestones
Passing critical retirement milestones without a clear flight plan can cost diligent savers tens of thousands in unexpected taxes, healthcare surcharges, and lost benefits. In this episode, Dr. Chris Mullis, PhD, CFP® breaks down key financial age triggers from 50 to 75 and addresses whether leaving a traditional IRA to a trust is a protective shield or an administrative nightmare. Tune in to discover how navigating the golden tax valley, timing Social Security, and structuring your estate can ensure your nest egg rocks retirement.
Retirement Big Picture
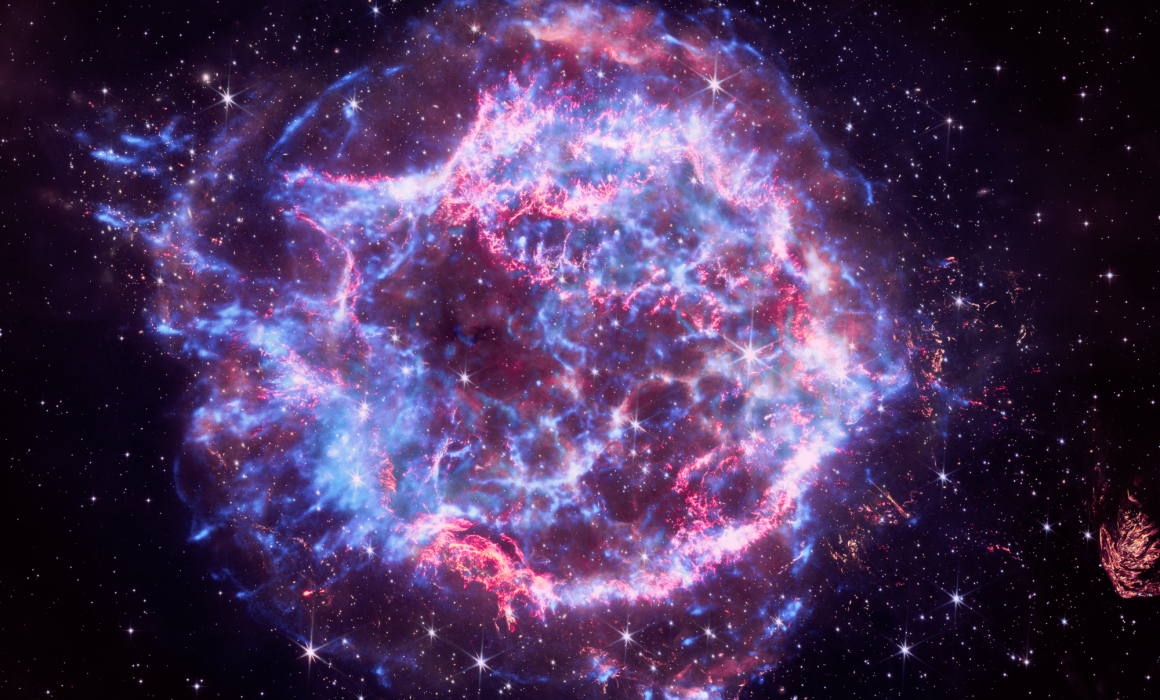
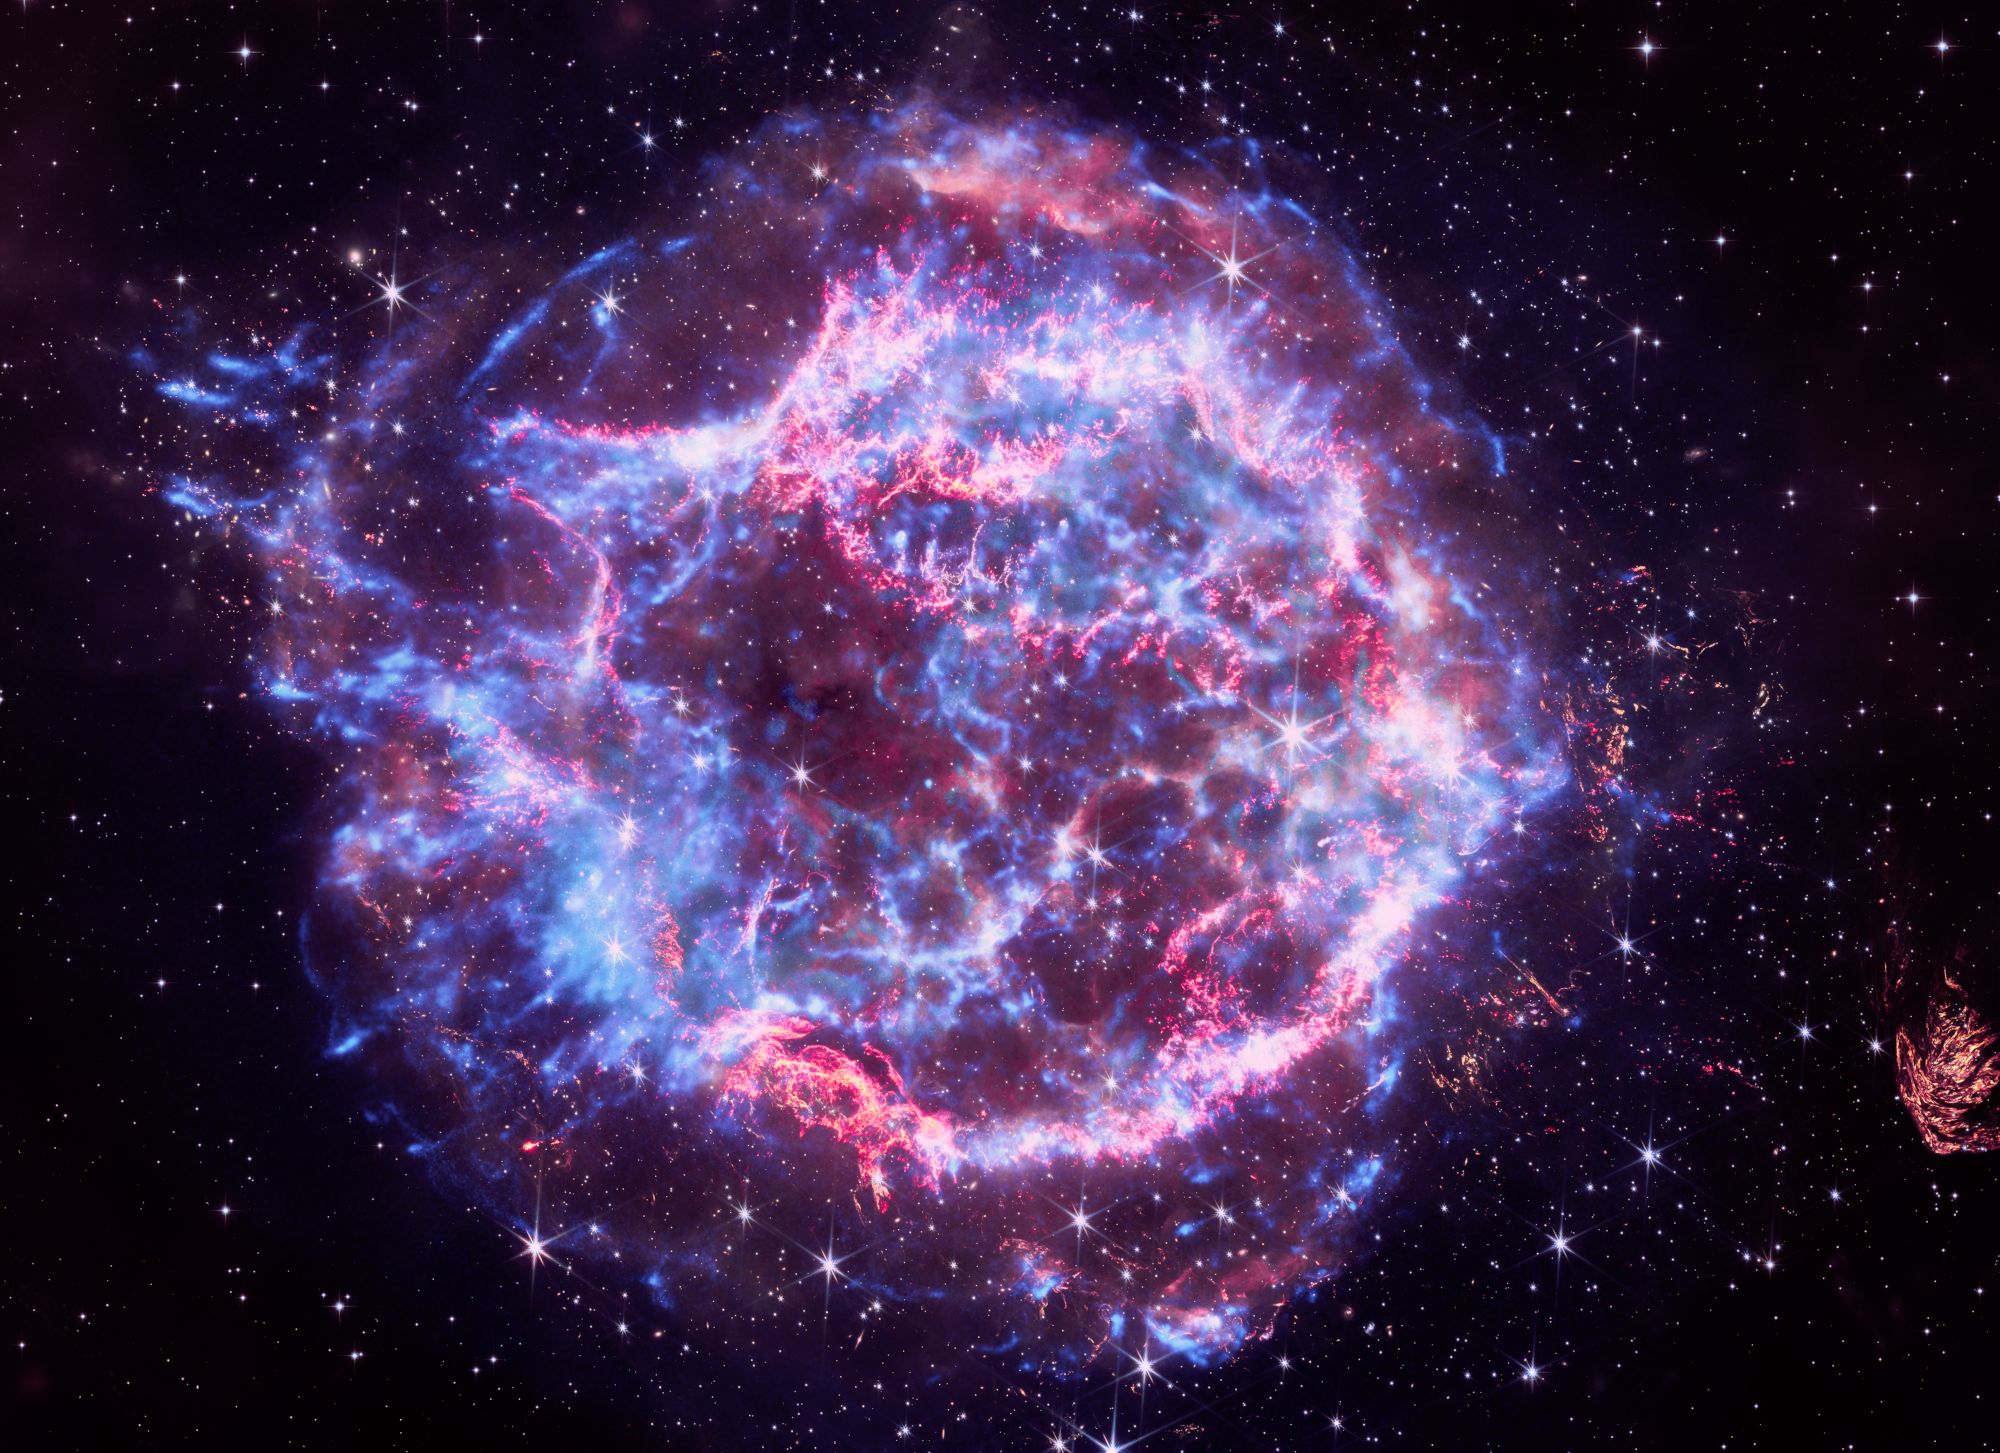
We examine a NASA composite image of the Cassiopeia A supernova remnant rendered in patriotic red, white, and blue to mark America’s 250th birthday. The picture combines Chandra X-ray Observatory data in brilliant blue—showing a superheated blast wave tearing outward at millions of miles per hour—with James Webb Space Telescope infrared data in vivid pinks and reds. This dual-telescope view captures both high-energy cosmic debris like iron and calcium and delicate glowing dust filaments that will eventually seed future solar systems.
Image Credit: NASA
Sign Up for The Launch
The Launch is a weekly email from Dr. Chris and his team. It’s full of retirement tips, news, listener questions & more, straight from us to your inbox. Get smarter about retirement in just 5 minutes every week. Let’s go!
Episode Transcript
Introduction
Dr. Chris Mullis, PhD, CFP®: Hi there, Dr. Chris here. Before we dive into today’s show, I wanted to answer a question I often get. That question is: What’s your day job when you’re not in the podcast studio? Well, I am a real live retirement planner and founder of Northstar Capital Advisors, and I’ve had the honor and the pleasure of walking this path with folks just like you, those approaching or in retirement.
And I’ve been on that journey with those great people for twenty-one years now. At Northstar, we provide truly comprehensive care, acting almost like a family office. From proactive tax planning to walking into attorney meetings alongside you for estate coordination, we dig deep into every detail of your financial life.
We track spending guardrails so you never underlive or overspend your wealth, and we analyze all your insurance coverage to keep your assets protected. Because we don’t sell any products at all, we only sell our advice, our only role is to serve as your tireless advocate. Knowing that every financial move affects another, our mission is to keep that entire big picture, your entire big picture, in clear view, aligning every piece of your plan with your core values and your personal goals.
You can check us out at retirednorth.com. Now, on to our show.
Retirement Briefing Room
Dr. Chris Mullis, PhD, CFP®: In rocket science, missing an orbital midcourse correction by a fraction of a degree can send a spacecraft thousands of miles off target into deep space. In retirement planning, passing key age milestones without a clear flight plan can cause you to leave tens of thousands of dollars on the table, be it in taxes, health insurance surcharges, or lost benefits.
Today, we’re mapping out your ultimate milestone mission map. Are you ready?
NASA: 3, 2, 1, 0 and lift off. Lift fell Americans return to space as discovery clears the tower.
Dr. Chris Mullis, PhD, CFP®: Welcome back to Retirement Isn’t Rocket Science. I’m your host, Dr. Chris Mullis. I’m a practicing retirement planner with twenty-one years of experience and founder of Northstar Capital Advisors, a retirement and tax planning firm. I spent my first career as an astrophysicist using NASA’s great space observatories and giant telescopes in Hawaii and Chile to map the outer edges of the universe.
Today, as a certified financial planner, I’m helping you navigate a different kind of frontier that’s no less important. That’s your retirement. If you haven’t already joined the crew, I invite you to subscribe to our weekly retirement newsletter, The Launch. This is where we share all the valuable resources, links, and action steps to make your retirement even better.
You can sign up for The Launch by visiting retirementisntrocketscience.com. Episode twenty-six begins now
Dr. Chris Mullis, PhD, CFP®: In today’s show, are you missing important retirement age milestones that could save you thousands? And is leaving your IRA to a trust a brilliant safeguard for your children’s future or an administrative drag that burns a hole in their inheritance?
And finally, cosmic fireworks. NASA unveils Cassiopeia A in patriotic red, white, and blue
Ask Mission Control
Dr. Chris Mullis, PhD, CFP®: Welcome to the Retirement Briefing Room. This is where we break down key financial moves, spotlight proven wins, and build a mission plan that puts your retirement on autopilot. Today, we’re analyzing an insightful piece titled “Retirement Milestone Ages Most People Miss and What to Do About Each,” written by Michael Pappas, CFP, and published in Kiplinger in August of this year.
Back when I was working in rocket science, every mission had pre-scheduled orbital burns, specific coordinates and time and space where engines fired to alter the spacecraft’s trajectory.
In retirement planning, the IRS has its own system of orbital markers. These are the milestone ages of fifty, fifty-five, fifty-nine and a half, sixty, sixty-two, sixty-three, sixty-five, seventy and a half, and seventy-three to seventy-five. But here is the critical difference. A checklist of dates tells you when a portal opens, but it doesn’t tell you how to navigate your actual life.
As I often point out with my clients, retirement is a life design challenge, not just a math problem. A static list of age triggers can easily breed information overload or false confidence. What we need is flexible and adaptive retirement planning, making iterative adjustments as your health goals and your values evolve.
So today, we’re taking this exceptional chronological breakdown from Kiplinger, and pairing it with real-world wisdom from my experience of helping pre-retirees and retirees walk this path for the past two-plus decades.
Let’s start on the launch pad with phase one. Pre-launch acceleration covering ages fifty to fifty-nine and a half. When you turn fifty, the catch-up contribution window officially opens. For twenty twenty-six, the standard 401k contribution limit is twenty-four thousand five hundred dollars.
But turning fifty allows you to add an extra eight thousand dollars, bringing your maximum annual contribution to thirty-two thousand five hundred dollars. For traditional and Roth IRAs, the standard twenty twenty-six limit is seven thousand five hundred dollars plus a one thousand one hundred catch up, bringing your ceiling to eight thousand six hundred dollars.
If you feel like your nest egg needs extra thrust, this is your moment to recalibrate. At age fifty-five, two more powerful tools unlock. First, if you’re enrolled in a high-deductible health plan, you can make a one thousand dollar HSA catch-up contribution, raising individual limits to five thousand four hundred and family limits to nine thousand seven hundred and fifty in twenty twenty-six.
The HSA is the undisputed superstar of tax efficiency. Pre-tax contributions, tax-free growth, and tax-free withdrawals for qualified medical costs. Now zooming out a bit, still on age fifty-five, the second key tool that opens up is you gain access to the rule of fifty-five.
If you separate from service during or after the calendar year in which you turn age fifty-five, you can take penalty-free withdrawals from your current employer’s 401or 403plan. Remember, this rule does not apply to IRAs or prior employer plans. Then, at age fifty-nine and a half, the ten percent early withdrawal penalty disappears across all standard tax-deferred accounts, unlocking penalty-free access
Now let’s interject some real-world wisdom here. While Michael correctly outlines these saving mechanisms, I frequently caution against accumulation bias.
Many diligent savers spend decades in accumulation mode, and hoarding extra cash late in their fifties can build a psychological wall that makes spending money in retirement feel extremely scary. Furthermore, I believe there’s a critical footnote at age fifty-nine and a half. Turning fifty-nine and a half does not give you instant tax-free access to all Roth funds.
You must still respect the Roth five-year rules, which require a five-year holding period for conversions and account history. Under Secure Act 2.0, if your prior year FICO wages exceed one hundred and fifty thousand dollars, your catch-up contributions must be made as Roth dollars. That’s actually a wonderful opportunity to build tax location diversity before you retire
Now let’s move to phase two, the golden tax valley and re-entry windows spanning ages sixty to sixty-five. For folks ages sixty, sixty-one, sixty-two, and sixty-three, Secure Act 2.0 introduced a super catch-up contribution window. In twenty-twenty-six, eligible participants in 401, 403, and 457 plans can make a super catch-up of eleven thousand two hundred and fifty dollars, bringing total potential workplace contributions to a staggering thirty-five thousand seven hundred and fifty dollars in a single year.
For widows and widowers, age 60 presents a pivotal Social Security opportunity. Surviving spouses can begin collecting survivor benefits as early as age 60. Survivor benefits are not subject to deemed filing. A surviving spouse can claim survivor benefits first while letting their own retirement benefit grow untouched up until age 70, or vice versa.
Failing to coordinate this decoupling strategy can leave tens of thousands of dollars on the table I think most people are familiar with the age sixty-two milestone, probably the most recognizable. At age sixty-two, early Social Security retirement benefits become available for everyone else. Claiming at age sixty-two results in a permanent reduction in monthly income compared to waiting until full retirement age or age seventy. While traditional math models favor waiting until seventy to maximize guaranteed inflation-adjusted income.
I believe retirees need to consider health span versus lifespan. Because health can decline in your late sixties, claiming Social Security at age sixty-two might be an ideal strategy if it funds your go-go travel years or keeps your income low enough to execute aggressive Roth conversions.
That brings us to age sixty-three, which is the milestone that stings people most if they aren’t paying attention. Medicare uses a two-year look-back to determine your Part B and your Part D premiums at age sixty-five. In twenty twenty-six, if your modified adjusted gross income at age sixty-three exceeds one hundred and nine thousand dollars for single filers or two hundred and eighteen thousand dollars for married couples, you hit IRMAA, the income related monthly adjustment amount. IRMAA operates as a sharp cliff. Crossing the threshold by just a single dollar triggers thousands in annual Medicare surcharges. But I want to emphasize that perspective matters. Don’t let the IRMAA dog wag the tax tail. The window between stopping work and starting mandatory distributions or Social Security is the golden tax valley.
Intentionally triggering a temporary IRMAA surcharge at age sixty-three by executing aggressive Roth conversions can shrink your taxable IRA balance, saving you far more in long-term income taxes than the Medicare surcharges costed you temporarily At age sixty-four and nine months, your seven-month Medicare initial enrollment window opens.
Missing it can cause permanent late enrollment penalties. Then at age sixty-five, Medicare begins, and active HSA contributions must stop.
Finally, let’s navigate phase three: cruising altitude and RMD defense. Covering ages seventy and a half to seventy-five. At age seventy and a half, charitable-minded retirees with traditional IRAs unlock qualified charitable distributions or QCDs. In twenty twenty-six, you can transfer up to one hundred and eleven thousand dollars per year or two hundred and twenty-two thousand dollars per year for married couples.
You can make that transfer directly from your IRA to a qualified charity tax-free. Initiating QCDs right at seventy and a half before mandatory distributions begin is a great tactic to shave down tax-deferred balances and reduce future tax bracket creep. Because at ages seventy-three to seventy-five, required minimum distributions, RMDs, become mandatory. RMDs start at seventy-three for those born between 1951 and 1959, and at seventy-five for those born in 1960 or later. If you fail to take an RMD, the IRS levies a steep twenty-five percent penalty on the missed amount. Massive forced RMDs can push you into higher tax brackets, make more of your Social Security taxable and trigger unexpected IRMAA surcharges.
Proactive planning through Roth conversions, QCDs, and withdrawal sequencing is essential to prevent RMD tax explosions.
Let’s summarize the four core takeaways from today’s mission plan. First, utilize catch-up limits at ages fifty and sixty to sixty-three, but guard against accumulation bias so you don’t become afraid to spend and enjoy the wealth you’ve built.
Second, optimize the tax valley between career departure and age seventy-three through strategic Roth conversions, looking at total long-term tax savings rather than fearing small IRMAA surcharges. Third, evaluate Social Security through the lens of healthspan and active go-go years rather than relying strictly on longevity spreadsheets.
And fourth, if you’re charitably inclined, start qualified charitable distributions at age seventy and a half to systematically trim your tax-deferred IRA balance before mandatory RMDs hit at seventy-three or seventy-five. Remember, financial milestones are meant to serve your life, not control it. The goal isn’t to build a perfect spreadsheet or to die with the largest IRA.
It’s to use your wealth to design an intentional, purposeful, and joyful retirement. Master the rules, align them with your values, and enjoy the ride. You’ll find a link to the retirement milestone ages most people miss article in the show notes and in our weekly newsletter. Now, let’s head over to Mission Control to answer your financial questions and get you retirement ready
Discovery Houston, 20 seconds to LOS. Tres Hothead. Nice to be in orbit.
Welcome to Ask Mission Control. This week’s question comes from Giselle, who writes in with a dilemma that a lot of diligent savers face as they approach retirement. Giselle writes, “Hi, Dr. Chris. My husband and I love your podcast. You make all this financial planning stuff sound like common sense instead of rocket science.
We’ve worked hard and saved diligently over the past thirty years, and the bulk of our nest egg is sitting in our traditional IRAs. We recently set up a trust to make sure our two adult kids are protected and have some financial guardrails when they eventually inherit our accounts. When I brought this up to a buddy of mine, he warned me to pump the brakes.
He said leaving an IRA to a trust is a massive tax trap and an administrative nightmare. Now we’re hesitating. Why is everyone so nervous about leaving an IRA to a trust? Is it really that big of a hassle, or is the extra protection worth the baggage?” , So is leaving a traditional IRA to a trust a massive tax trap and administrative nightmare? The short answer is it can be if structured incorrectly, but it certainly doesn’t have to be. Think of it this way. In aerospace engineering, every extra piece of equipment you add to a rocket payload increases mass, which requires extra fuel and creates aerodynamic drag.
A trust attached to an IRA is very similar. It adds administrative drag. The real question isn’t whether drag exists, but whether the protection and control you gain are worth the extra baggage. Let’s break down why people get nervous, starting with the tax myth.
The main reason folks warn about a tax trap is that trusts hit the highest income tax bracket ridiculously fast. As an individual, you don’t hit the top thirty-seven percent federal tax bracket until your income clears over half a million dollars. A trust, on the other hand, slams into that top bracket at just around fifteen thousand dollars of retained income.
If an IRA distributes a hundred thousand dollars into a trust and that money sits inside the trust, the IRS takes a massive chunk at the top-tier rates. That sounds scary, but here’s what most people miss. The trust doesn’t necessarily have to pay that tax rate. Depending on how the trust terms are written, if the trust distributes that income to your children, that income gets carried out on a Form K-one and is taxed at your beneficiary’s personal tax rate.
Unless the trust retains the income, you can completely sidestep that highest trust tax bracket. The second concern is whether the trust qualifies as a see-through trust. To ensure your beneficiaries can utilize the full ten-year distribution window under the Secure Act rather than being forced into an immediate payout, the trust must meet basic criteria.
It must be valid under state law, become irrevocable at death, and have clearly identifiable beneficiaries. Please know these are not huge hurdles, and the vast majority of trusts drafted by experienced estate attorneys qualify without issue.
So what about the administrative nightmare part? That is a fair concern. Routing an IRA through a trust does mean additional tax returns, K-one filings, ongoing trustee duties, and potential professional fees. It’s a classic cost-benefit trade-off. What are you getting in exchange for that additional cost and complexity?
You get control, asset protection from potential divorces or lawsuits, and behavioral guardrails for your kids. If your kids are financially mature and stable, naming them as direct beneficiaries might be the cleanest orbit. But if they need protection, the trust’s benefits far outweigh the administrative baggage.
Just to summarize the key takeaways before we move forward. Number one, taxes can be managed. Income passed through to your children carries out on a K-one and is taxed at their individual rates, avoiding high trust tax brackets. Number two, see-through trust rules are straightforward. A properly drafted trust easily meets state law and beneficiary requirements to maintain standard distribution rules. And number three, weigh protection against complexity. The extra tax filings and administrative tasks are only worth it if your kids genuinely need protection or financial guardrails. Giselle, thanks so much for this interesting question and allowing us to navigate the IRA to trust trajectory and really thinking through balancing asset protection against administrative drag.
If you’ve got a question that you’d like us to answer on the show, head over to retirementisntrocketscience.com and click ask a question, or you can skip to the front of the line by calling Mission Control at seven, zero, four, two, three, four, six, five, five, zero and record an audio question
Now let’s leave behind the universe of trusts and IRAs and take a close look at a new JWST and Chandra X-ray image that provides an unprecedented view of a supernova remnant
NASA: In Discovery Houston, we’ve got a good picture of Steve.
Retirement Big Picture
Dr. Chris Mullis, PhD, CFP®: Welcome to the Retirement Big Picture part of the show. This is where we look up and look out to expand our appreciation and understanding of our amazing universe.
To mark the 250th birthday of the United States, nASA released a series of jaw-dropping celestial images rendered in patriotic red, white, and blue. And front and center of this cosmic salute is one of the most famous deep sky objects in astronomical history, a supernova remnant known as Cassiopeia A, or Cas A for short.
So what exactly are we looking at here? Cas A is the glowing, expanding debris field left behind by a massive star that ran out of fuel and blew itself apart in a cataclysmic explosion about 11,000 light years away, still within our Milky Way galaxy. Cassiopeia is one of the easiest constellations to spot. It forms a very distinct, bright W in the night sky, and it is absolutely visible over the United States.
Can an amateur astronomer see Cas A?
Well, if you walk outside a clear night, you can easily spot the W of Cassiopeia, of course, with your naked eye. However, Cas A itself, the ghostly cloud of expanding star stuff, is quite a challenge visually. Through a backyard telescope eyepiece, it appears as a very, very faint, subtle smudge. But dedicated amateur astronomers equipped with specialized narrow band filters and modern astrophotography cameras can capture breathtaking images of Cas A right in their backyards.
Professional astronomers also study it extensively from the ground using massive optical facilities and giant radio observatories like the Very Large Array in New Mexico. Yet, to get the full picture, you have to leave Earth’s atmosphere way behind.
Over the decades, NASA’s great observatories, from the Hubble Space Telescope to the Spitzer Space Telescope, have spent hundreds of hours studying Cas A. But this new birthday image brings together two of NASA’s most advanced space telescopes, the Chandra X-ray Observatory and the James Webb Space Telescope.
In this composite image, Chandra’s high-energy X-ray vision is rendered in brilliant blue. Chandra captures the blisteringly hot blast wave tearing outward through space at millions of miles per hour. It highlights superheated cosmic debris packed with heavy elements like iron, calcium, and oxygen. It’s a wonderful reminder that the very iron in our blood and the calcium in our bones were forged inside ancient stellar furnaces just like Cas A.
Meanwhile, the James Webb Space Telescope provides the infrared detail, shown here in vivid pinks and red. Webb’s powerful instruments pierce right through cosmic dust, uncovering delicate structures within the expanding shell of gas that previous telescopes could never resolve. Webb reveals cool cosmic dust grains and delicate glowing filaments, showing us how energy and material are mixing inside the explosion.
What Webb shows us is that a supernova isn’t merely a destruction event, it’s a cosmic garden. These scattered elements will eventually seed future solar systems, planets, and perhaps life itself. It’s a striking reminder that in the grand architecture of the universe, the end of one chapter is simply the catalyst that creates something new and wonderful for the future. You’ll find the Chandra plus JWST image of Cassiopeia A in this week’s newsletter that’s called The Launch. You can sign up for The Launch at retirementisntrocketscience.com.
Conclusion & Action Items
Dr. Chris Mullis, PhD, CFP®: Before you hit the ground running, here is your retirement mission checklist. These are the important actions you should tackle this week to make your retirement even better.
Number one: conduct an age milestone audit. Map out your personal timeline for the next five to ten years, identifying exactly when you cross these key ages: fifty-five, fifty-nine and a half, age sixty to sixty-three, age sixty-three IRMAA look back, sixty-five, seventy and a half, and RMDs at seventy-three or seventy-five.
You want to do this so you can anticipate tax and healthcare triggers proactively. Number two: evaluate your tax valley strategy. Review your pre-tax IRA and 401balances with a certified financial planner to model multi-year Roth conversions during your lower-earning gap years between the start of retirement and the onset of required minimum distributions at age seventy-three or seventy-five.
And number three: assess your Social Security and health span plan. That means align your Social Security claiming strategy with your health, active lifestyle goals, and overall income plan rather than defaulting to generic rules of thumb. This is Dr. Chris reminding you that you are both the commander and the pilot of your retirement mission.
Take control of your financial timeline today because with smart planning, retirement isn’t rocket science
Credits
Dr. Chris Mullis, PhD, CFP®: We thank the National Aeronautics and Space Administration for providing the radio communications between the space shuttle astronauts and the flight controllers.
Disclaimer
This show is for informational and entertainment purposes only. It is not specific tax, legal, or investment advice. Before considering acting on anything you hear in this show, first consult your own tax, legal, or financial advisor