Medicare Is NOT Set-and-Forget: Avoid Costly Traps Before Dec 7th (+ Why Bond Funds Beat Individual Bonds)
Leaving your Medicare plan on autopilot during open enrollment can quietly expose your retirement nest egg to sudden prescription price spikes and massive tax surcharges. In this episode, Dr. Chris Mullis, PhD, CFP® reveals how to dodge costly healthcare traps, manage multi-year tax brackets, and leverage bond funds as an all-weather income engine. Tune in to master your retirement cash flow and discover how a thousand-year-old cosmic collision delivers an inspiring message for your next great chapter.
Retirement Big Picture
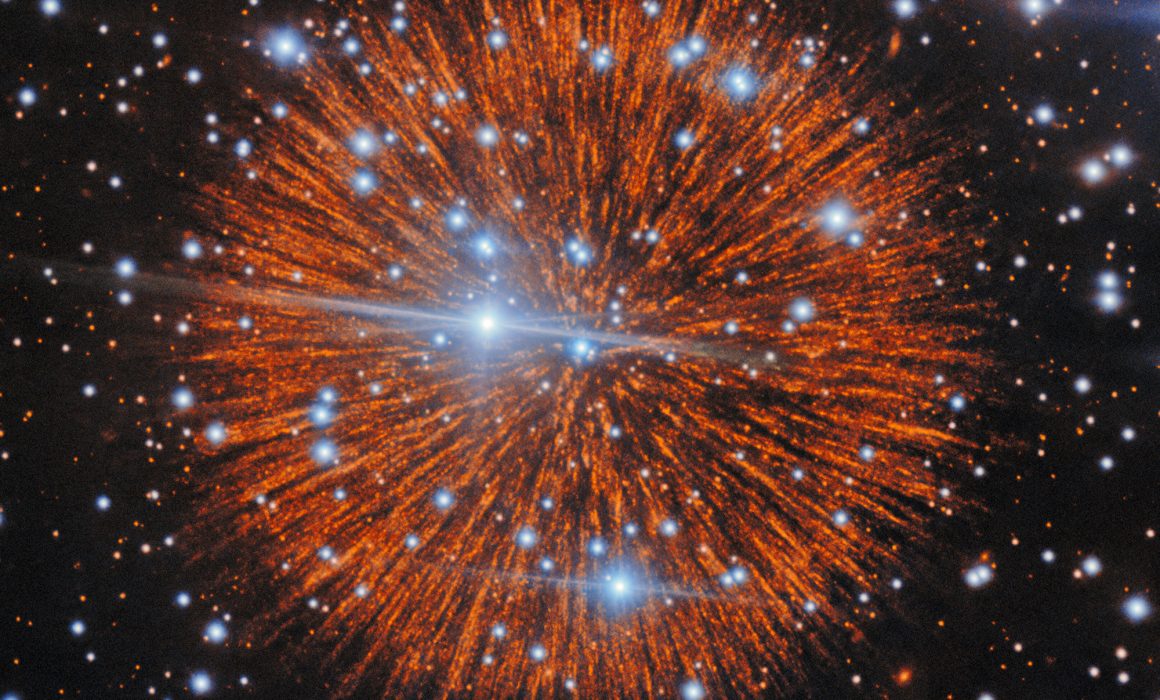
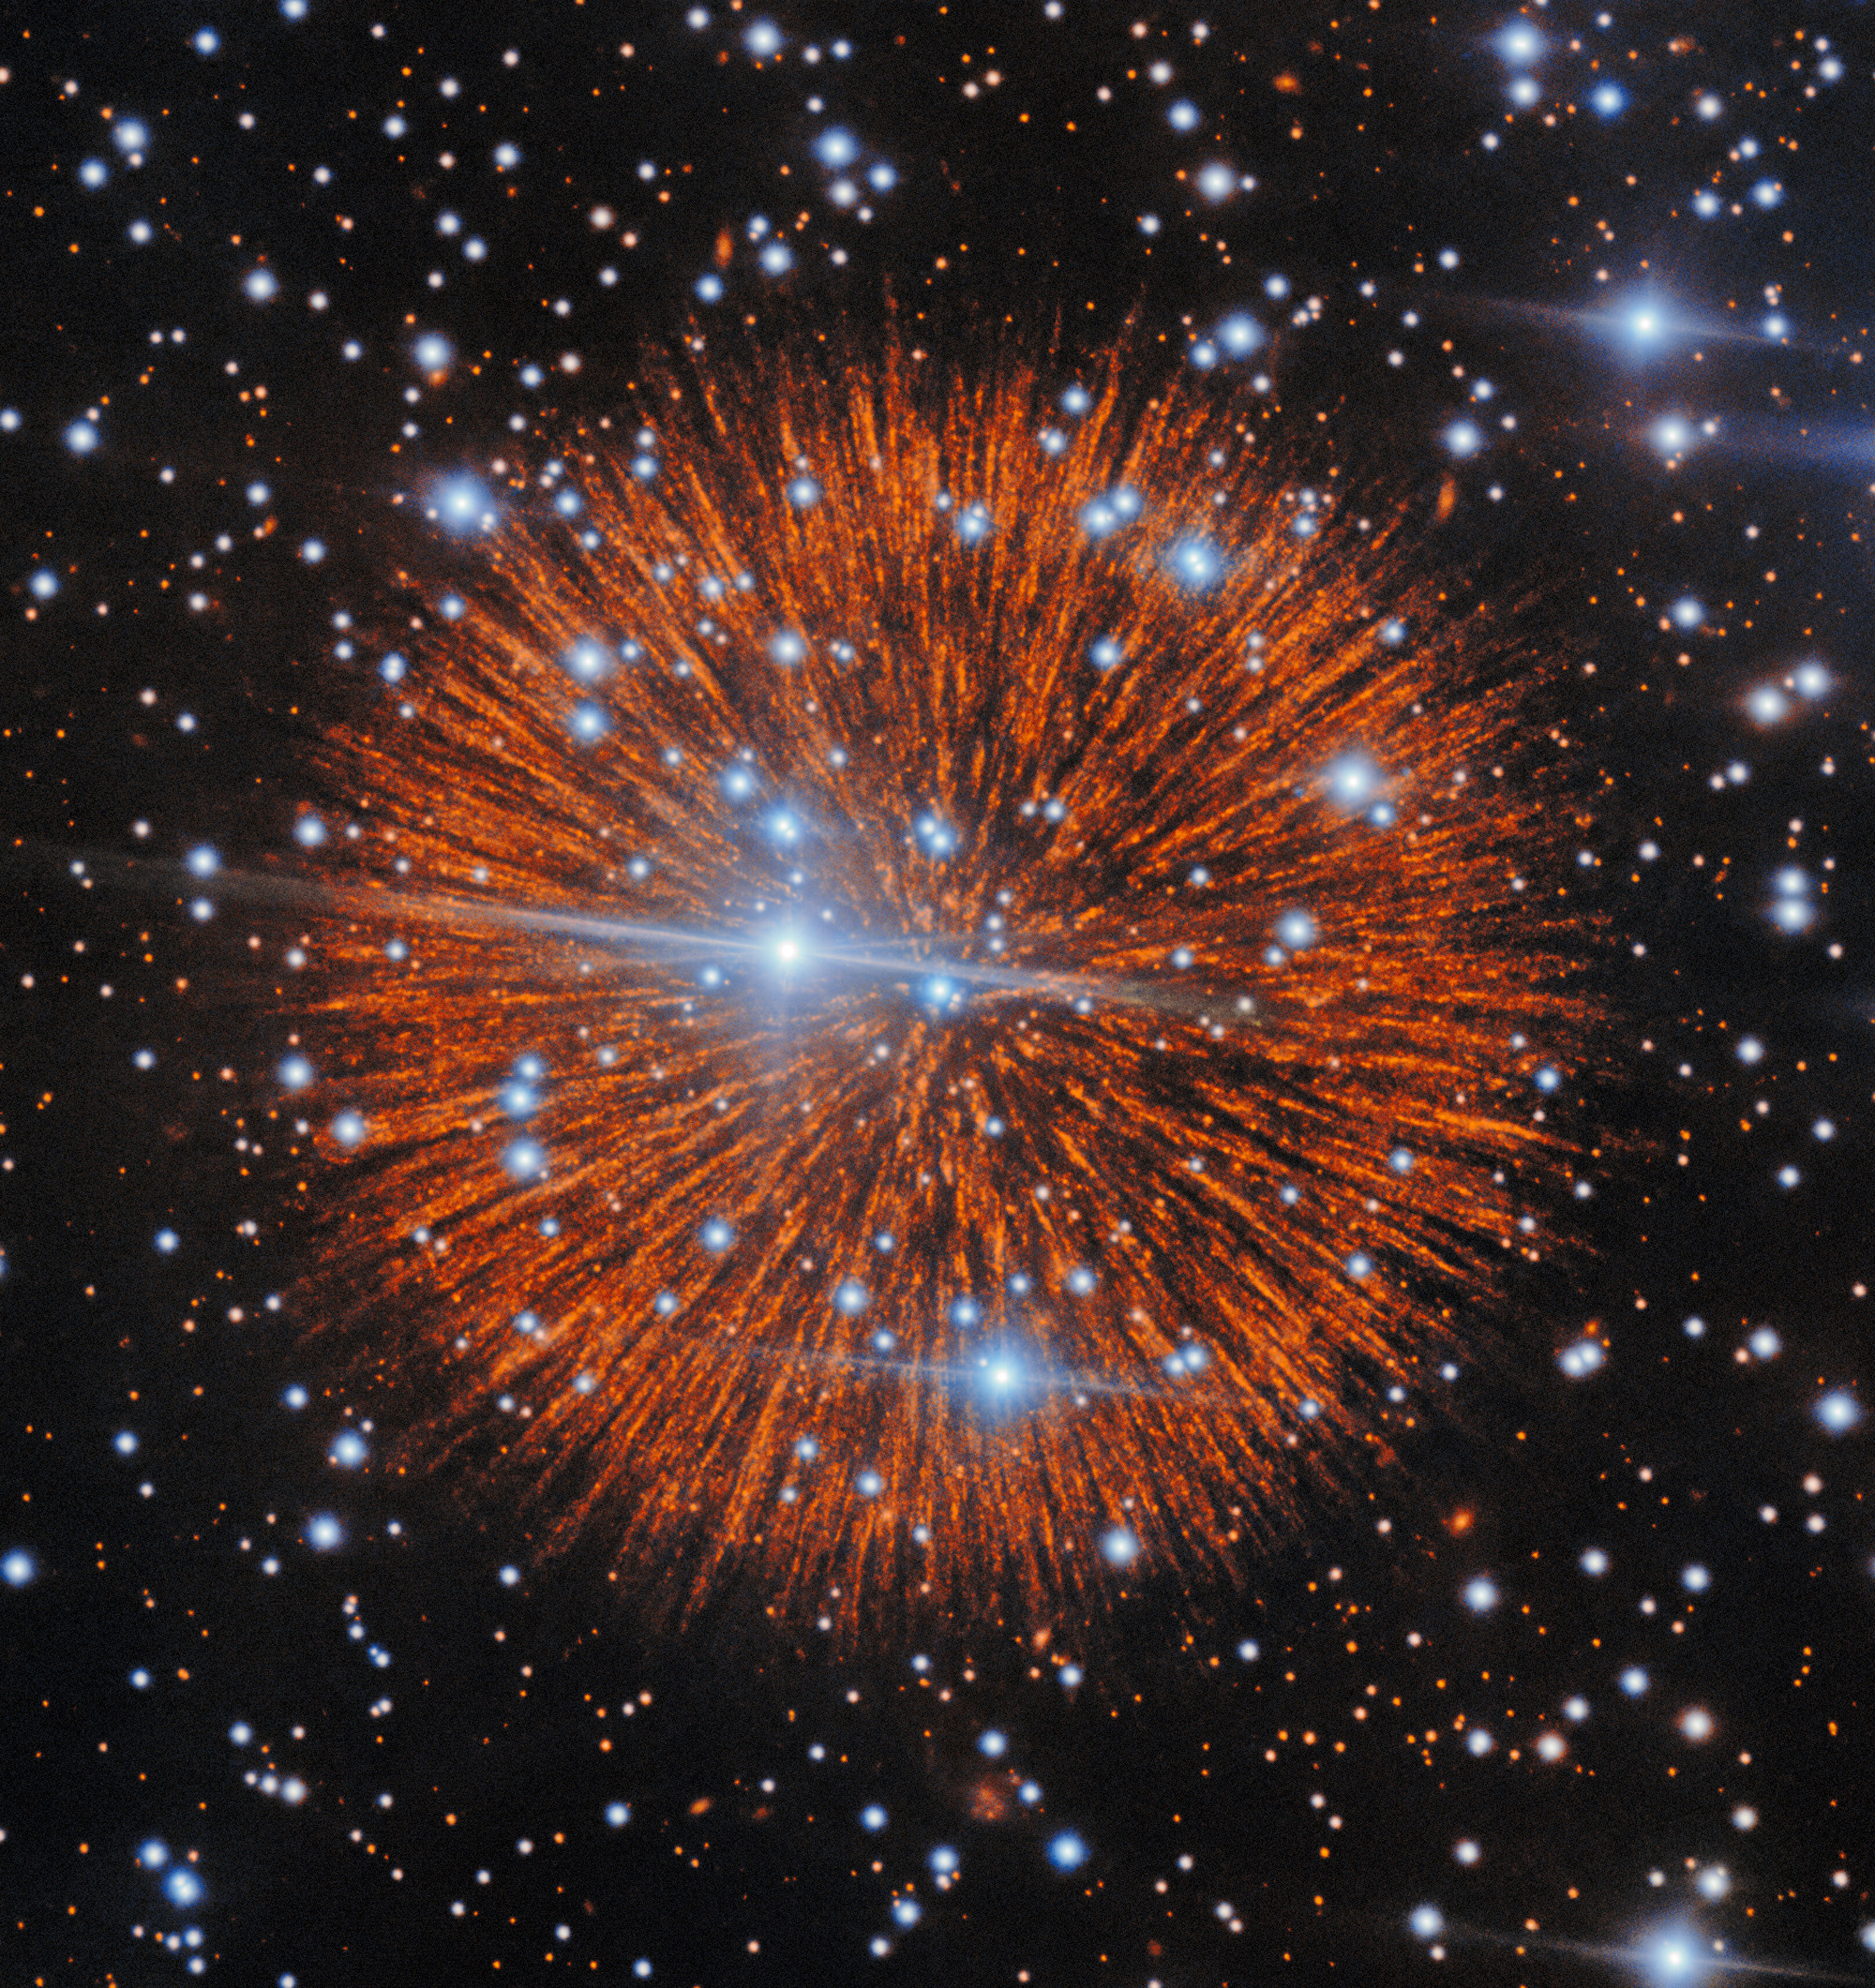
The stunning image of supernova remnant Pa 30 in Cassiopeia resembles a celestial Fourth of July display and a brilliant, glowing cosmic dandelion. High-resolution telescope views reveal long radial filaments of sulfur expanding outward at 1,100 kilometers per second from an unusual white dwarf star collision. Imagery from the Gemini North Telescope pierces through cosmic dust to uncover a detailed three-dimensional shell of tattered tendrils carved by intense stellar winds surrounding a central, surviving zombie star.
Image Credit: International Gemini Observatory/NOIRLab/NSF/AURA
Sign Up for The Launch
The Launch is a weekly email from Dr. Chris and his team. It’s full of retirement tips, news, listener questions & more, straight from us to your inbox. Get smarter about retirement in just 5 minutes every week. Let’s go!
Episode Resources
Episode Transcript
Introduction
Dr. Chris Mullis, PhD, CFP®: Every year between October 15th and December 7th, millions of retirees leave their healthcare plans on autopilot, unwittingly setting themselves up for a massive pharmacy price spike and a potential multi-thousand dollar tax surcharge. Today, we’re unpacking how you should navigate Medicare’s annual enrollment season to protect your income and keep your retirement mission strong.
Are you ready?
NASA: 3, 2, 1, 0 and lift off. Lift fell Americans return to space as discovery clears the tower.
Dr. Chris Mullis, PhD, CFP®: Welcome back to Retirement Isn’t Rocket Science. This is episode 29. I’m your host, Dr. Chris Mullis. I spent my first career as an astrophysicist using NASA space telescopes to map the outer edges of the universe. Today, as a certified financial planner and retirement firm owner, I’m helping you steer clear of financial black holes that threaten your hard-earned retirement.
Our mission is clear: lower your taxes, strengthen your portfolio, and give you the confidence and the capacity to spend more. Buckle up. We’re going to master your money and explore the mysteries of the universe along the way.
In today’s show, is your health plan on autopilot when it shouldn’t be? The $4,000 Medicare traps you want to avoid. In our listener question segment, we learn why bond funds are the Swiss Army knife of a multi-decade retirement portfolio. And finally, heading out to deep space, the zombie star of Cassiopeia, how cosmic collisions create spectacular second acts
Retirement Briefing Room
Dr. Chris Mullis, PhD, CFP®: Welcome to the Retirement Briefing Room. This is where we pull up the blueprint on your financial life, focusing on what actually works and mapping out clear, actionable steps for your retirement mission. Now, if you are age sixty-five or older, or approaching that milestone, you know that October marks the start of Medicare’s annual enrollment period, which runs from October 15th through December 7th every year.
When you’ve spent forty years building a healthy nest egg, it can be easy to view open enrollment as a minor administrative hassle. You might think, “My health hasn’t changed. My doctors are great, so I’ll just let everything auto-renew.” In the financial planning world, that is what we call an unforced error.
Medicare is not a static set it and forget it program. It’s a dynamic financial system where small unnoticed policy shifts can trigger thousands of dollars in unnecessary expenses. Today, we’re walking through how my retirement planning firm, NorthStar Capital Advisors, handles open enrollment with our clients, and how you can apply those exact same strategies and principles to safeguard your retirement cash flow. And if you want help with this, visit retirenorth.com to schedule an introductory phone call.
First, let’s address the biggest rule we advocate: never fly on autopilot. Every September, insurance carriers send out a document called the Annual Notice of Change, or ANOC. Far too many retirees toss this straight into the recycling bin.
But insurance companies adjust their drug lists, known as formularies, along with pricing tiers, deductibles, and preferred pharmacy networks every single year. Even if your health status or prescriptions haven’t changed one bit, the cost structure beneath your plan almost certainly has. Financial planners call this the Part D formulary trap. Imagine you take a daily brand name prescription. Last year, your plan classified this as a tier three preferred medication with a modest copay. But heading into the new year, the insurance company reclassifies that exact same drug as a tier four specialty medication.
If you let the plan auto-renew, you could wake up in January to find your out-of-pocket prescription expenses spiking by thousands of dollars. The same risk applies to pharmacy networks. Drug plans partner with specific pharmacy chains as preferred pharmacies. You might pay a ten dollar copay at a preferred pharmacy versus a forty-five dollar copay at a standard retail pharmacy under the exact same plan.
If your local pharmacy loses its preferred status for the coming calendar year, and you don’t catch it, your copays double overnight for doing nothing differently How can you solve this? At Northstar, we recommend taking your exact list of prescription medications, including exact dosages and frequencies, and inputting them directly into medicare.gov’s Plan Finder tool, and you should do this every October.
You select your preferred local and mail order pharmacies, and the tool automatically calculates your total expected out-of-pocket costs, combining annual premiums, co-pays, and deductibles across every available plan in your zip code. It only takes about twenty minutes and routinely saves retirees hundreds or thousands of dollars for the upcoming year.
Another critical distinction I must highlight involves Medicare Advantage versus Medigap policies. During open enrollment, you can freely switch between prescription drug plans or Medicare Advantage plans without health questions. However, if you are currently on Medicare Advantage and wish to switch back to original Medicare with a Medigap supplement, in most states, you do not have a guaranteed issue right.
You may have to go through medical underwriting, and if you have pre-existing conditions, you could be denied coverage or charged significantly higher rates. That’s why checking provider networks for primary doctors, specialists, and regional health systems before making any plan shifts is absolutely paramount.
This brings us to a key strategic framework. Separate macro strategy from specialized execution. A fiduciary-feeling advisor like my firm cannot and will not try to sell insurance products or act as granular insurance agents. Instead, we focus on high-level navigation, modeling long-term retirement cash flow, managing tax brackets, and tracking healthcare cost assumptions.
When it comes to detailed insurance navigation, top planners partner with independent Medicare brokers and experts such as Daniel Roberts and her team at Boomer Benefits, who represent multiple carriers. These independent specialists run granular comparisons, verify hospital networks, and act as client advocates during claims disputes, all at zero direct costs to our clients. It’s about building a coordinated team. Your certified financial planner manages the flight trajectory while independent health specialists handle the specific flight gear.
Now, let’s explore the heavy-duty financial intersection where Medicare meets tax planning, and that’s unfortunately IRMAA surcharges. Tax planning is a year-round process at my firm, and we spend significant time protecting our clients from IRMAA, the Income Related Monthly Adjustment Amount. Here’s the key rule: Medicare Part B and Part D premiums are determined by your Modified Adjusted Gross Income, or your MAGI, from two years prior.
That means financial decisions you make today in twenty twenty-six directly dictate your Medicare premiums in twenty twenty-eight. I must underscore that IRMAA thresholds act as strict tax cliffs. If your income exceeds a tier threshold by even one single dollar, you don’t just pay a higher tax rate on that extra dollar. You trigger a full monthly premium surcharge across both Part B and Part D for the entire year.
For a married couple, stepping over a threshold by a single dollar can add upwards of four thousand dollars in unexpected annual Medicare premiums
Here’s a common real-world scenario. A person wants to execute a large single-year Roth conversion, say one hundred and fifty thousand dollars, to reduce future requirement of distributions and reduce their lifetime tax bill.
On paper, getting money into a Roth sounds great, but when you model the move against Medicare’s two-year look-back, that lump sum conversion triggers high tier IRMAA surcharges, potentially wiping out a good portion of the tax benefit of that Roth conversion. Instead, by spreading that Roth conversion out over multiple years in calculated amounts just below the IRMAA tier cliff, you achieve tax-free growth without triggering premium penalties. What if you’ve already crossed the threshold because you recently retired or stopped working? There’s a vital rescue mechanism, and that’s called Form SSA-dash-forty-four. Because Medicare looks back two years, a newly retired client might receive a notice stating their premiums are skyrocketing based on their higher earnings from two years ago when they were still working full time.
If you’ve experienced a qualifying life-changing event such as work stoppage, work reduction, or marriage changes, you can file an SSA-dash-forty-four with Social Security along with proof of your lower retirement income.
This appeals the initial determination and resets your Medicare premiums to a standard base rate based on your current reality, saving thousands of dollars in unfair surcharges. For our clients who are still working, we remind them that healthcare in retirement shouldn’t be viewed as a terrifying gatekeeper that forces you to stay in a job you dislike until age sixty-five.
It is simply a manageable line item expense that can be modeled, optimized, and controlled with proactive tax and withdrawal strategies. Before we wrap up today’s briefing, let’s summarize the key flight rules for your Medicare enrollment season. First, never leave your healthcare coverage on autopilot. Review your annual notice of change every fall, and run your exact medication list through medicare.gov to protect against drug tier changes and pharmacy network traps.
Second, separate strategic planning from specialized execution. Rely on your CFP for multi-year tax and income modeling, and leverage independent Medicare experts to audit carrier plans and doctor networks. Third, mind the two-year IRMAA look-back rule. Coordinate Roth conversions, capital gain harvests, and portfolio withdrawals to stay just below the IRMAA tax cliffs, and file form SSA-44 if a recent retirement triggers undeserved surcharges.
Navigating Medicare during retirement isn’t about guessing what the healthcare system will do next. It’s about putting proactive financial flight controls in place. When you align your health insurance coverage with a multi-year tax and income plan, you eliminate costly surprises, keep more of your hard-earned wealth working for you and gain peace of mind to focus on what truly matters in this exciting chapter of life. Now, let’s head over to Mission Control to answer your financial questions and get you retirement ready
Ask Mission Control
Welcome to Ask Mission Control. This week’s question comes from David, who asks, “Hey, Dr. Chris, longtime listener. I understand why folks like individual bonds in retirement. You know exactly what interest you’re getting and when you get your principal back, but I keep hearing you financial folks talk about bond funds.
If bond funds don’t mature and their prices fluctuate, why would someone choose a bond fund over buying individual bonds directly?” David, thank you for sending that one in. You’ve hit on one of the most common questions I get from diligent savers preparing for retirement. On paper, holding an individual bond feels comfortably predictable.
It feels like launching a space probe on a direct trajectory. You lock in your launch date, plot your flight path, and know the exact date it touches down on Earth to return your principal. So why do so many retirement planners often favor broad bond ETFs instead of individual bonds?
It comes down to five reasons in my experience and opinion. Those are default protection, daily liquidity, rebalancing power, yield reinvestment, and operational simplicity. Let’s go through those one by one. First, risk and diversification. When you buy an individual corporate or municipal bond, your money relies entirely on the financial health of that single company or municipality.
If that institution runs into severe turbulence, your principal takes a direct hit. That’s single-issuer default risk. Broad bond ETFs or bond funds, however, provide an instant diversification across thousands of bond issues on a single ticker. Instead of placing your entire mission on one engine, you’re deploying an entire fleet.
If one bond stumbles, the impact on your multi-million dollar nest egg is practically unnoticeable. Second, practical retirement income. I think a well-structured stock and bond fund portfolio as a Swiss army knife, an all-weather multi-tool designed for a twenty or thirty-year retirement decumulation journey.
During stock market drawdowns, your broad bond ETF serves as a crucial portfolio ballast and income source. Instead of being forced to liquidate equities at a loss to fund your monthly lifestyle, you can draw your distributions directly from your liquid bond ETF, giving your stocks the necessary breathing room to recover.
Third, bond ETFs offer unmatched daily liquidity and systematic rebalancing. When a CFP professional manages your risk, we regularly rebalance, trimming stock gains into bonds during bull markets or using bond ETFs to buy equities on sale during market downturns. Doing that with dozens of individual bonds creates major administrative friction filled with illiquid bid-ask markups, commissions, and lock-up periods. A bond ETF eliminates all that noise with one click. Fourth, bond ETFs handle interest rate changes automatically over multi-decade horizons.
Open-ended bond ETFs hold rolling portfolios. As interest rates rise over your retirement, the ETF continually reinvests maturing bond proceeds into newer bonds at higher prevailing yields. You don’t have to guess rate cycles or hunt for new bonds. The fund automatically captures higher yields to protect your long-term purchasing power against inflation.
Fifth and final, operational simplicity. Managing a ladder of dozens of individual bond line items introduces unnecessary overhead when coordinating required minimum distributions, tax loss harvesting, or estate planning. Bond ETFs provide low-cost, transparent, hands-off efficiency.
David, thanks again for submitting your excellent question. If you’ve got a retirement or just a financial question in general that you’d like us to answer on the show, head over to retirementisntrocketscience.com and click Ask a Question. Or even better, head to the front of the line by calling Mission Control and recording your audio question by calling 704-234-6550.
Now, let’s look at what happens if a star survives its own explosive death a thousand years ago, only to create a breathtaking second act that astronomers are still admiring today
NASA: In Discovery Houston, we’ve got a good picture of Steve.
Retirement Big Picture
Dr. Chris Mullis, PhD, CFP®: Welcome to the Retirement Big Picture part of our show. This is where we pause to look up and look out to expand our appreciation and knowledge of our amazing universe. A long time ago, in a galaxy not far, far away, I spent nearly two decades studying the cosmos as an observational astrophysicist, so this is a subject I love dearly.
Today, we are gazing at a cosmic spectacle that looks less like a standard star and more like a magnificent celestial Fourth of July display. It’s known as Paw 30, a breathtaking supernova remnant nestled in the northern constellation of Cassiopeia If you step outside on a clear evening anywhere in the United States, Cassiopeia is remarkably easy to spot.
It forms that bright, familiar W or M pattern in the northern sky, and because it’s circumpolar for most of North America, it stays visible in our night sky all year round. Now, while Cassiopeia itself is easily visible to the naked eye, the Pa 30 nebula is a ghostly phantom.
You simply cannot see it through a standard backyard telescope. ironically , It wasn’t discovered at a major professional observatory, but by a dedicated amateur astronomer named Dana Patchak in twenty thirteen. Dana discovered it while carefully analyzing public archival infrared data gathered by NASA’s WISE mission, the Wide-field Infrared Survey Explorer.
When Dana spotted this rare cosmic structure, it was cataloged as Pa 30, with Pa or P-A standing for Patchak, and 30 marking his thirtieth deep sky discovery. Dana’s pretty good at this. What makes Pa 30 so extraordinary is its historic origin story. Back in the year eleven eighty-one, sky watchers in ancient China and Japan documented a bright new guest star, that’s what they called supernova back then, guest star, that appeared in Cassiopeia.
For nearly a thousand years, astronomers wondered what became of that historic stellar explosion cataloged as SN 1181, Supernova 1181. Pa 30 turned out to be the long-lost remnant. This wasn’t an ordinary stellar death. Pa 30 resulted from an exceptionally rare Type 1AX supernova. Careful research revealed that two ultra-dense white dwarf stars spiraled together, colliding in a violent merger.
Normally, a supernova completely obliterates the progenitor stars. But in this unique collision, the explosion left behind a surviving zombie star at the center, surrounded by an expanding shell of superheated gas and warm cosmic dust. To untangle this mystery, astronomers deployed some of humanity’s most advanced observatories. Ground-based professional facilities like the eight-meter Gemini North Telescope in Hawaii captured high-definition optical images using Gemini’s Multi-Object Spectrograph. Their pictures revealed long radial filaments of sulfur glowing like a giant cosmic dandelion expanding outward at eleven hundred kilometers per second. Space observatories like NASA and ESA’s XMM Newton X-ray Telescope analyzed its chemical nature, revealing heavy concentrations of neon, magnesium, silicon, and sulfur, but absolutely no hydrogen or helium.
Most recently, NASA’s James Webb Space Telescope turned its powerful infrared eyes on Pa thirty. Webb’s Mid-Infrared Instrument pierced through the dust to capture a groundbreaking three-D view of these glowing sulfur tendrils. Webb revealed that these tattered filaments are original supernova ejecta being carved into long wakes by ongoing stellar winds.
And that central survivor star? It’s a rapidly rotating heavyweight blasting out winds at a record-breaking sixteen thousand kilometers per second with surface temperatures soaring nearly two hundred thousand degrees Kelvin. Astrophysics predicts this unstable white dwarf is so massive it will eventually collapse into a neutron star within ten thousand years.
There’s a wonderfully inspiring lesson behind Pa thirty. Here is a star system that underwent a violent, life-altering collision nearly a thousand years ago. Yet it didn’t vanish into the darkness. It reinvented itself in a spectacular second act, creating a vibrant, luminous structure that continues to captivate astronomers across the centuries. As you approach or enjoy your own retirement, remember that entering this stage of life isn’t an ending either. It is your opportunity to launch an exciting new chapter, cultivate new passions, and shine brighter than ever before.
You will find an absolutely stunning image of Pa 30 in this week’s newsletter called The Launch, and that image is so unique in its presentation. I actually had to look at it twice. I thought it was a computer simulation because the symmetry and the detail are so, so rich. So be sure to check it out. If you’re not already receiving our weekly newsletter, you can sign up for it at retirementisntrocketscience.com.
Conclusion & Action Items
Dr. Chris Mullis, PhD, CFP®: Before hitting the ground running, here’s your retirement mission checklist. These are important actions you should tackle this week to make your retirement even better. Number one, audit your prescription list on medicare.gov. Gather your current prescription medications, exact dosages, and preferred local pharmacies.
Then run them through medicare.gov’s Plan Finder tool before December 7th to verify your plan remains the lowest total cost option for next year. Number two, review your ANOC letter for doctor network changes. Read your Annual Notice of Change, letter from your current carrier, especially if you hold a Medicare Advantage plan, to confirm your primary physicians, specialists, and preferred hospital systems remain in-network for the upcoming calendar year.
And number three, evaluate your MAGI against IRMAA thresholds. Work with your financial planner to model any end-of-year tax moves, such as Roth conversions or capital gains realizations, and model them against the two-year Medicare MAGI look-back brackets.
That’s a mouthful. Remember, MAGI is Modified Adjusted Gross Income, and IRMAA is the Income-Related Monthly Adjustment Amount, which are Medicare premium surcharges. If you recently retired or reduced your work hours, ask your advisor about filing a form SSA-44 to appeal and lower your current premium surcharges.
This is Dr. Chris reminding you, you are both the commander and the pilot of your retirement mission. Take control of your trajectory today to worry less and retire more because with thoughtful planning, retirement isn’t rocket science.
Credits
Dr. Chris Mullis, PhD, CFP®: We thank the National Aeronautics and Space Administration for providing the radio communications between the space shuttle astronauts and the flight controllers.
Disclaimer
This show is for informational and entertainment purposes only. It is not specific tax, legal, or investment advice. Before considering acting on anything you hear in this show, first consult your own tax, legal, or financial advisor