What the Fed rate hike likely means for you
In this special first-anniversary episode, Dr. Chris Mullis, PhD, CFP® breaks down what the Federal Reserve’s latest interest rate hike really means for your retirement nest egg and why reacting to media headlines is a classic rookie mistake. Discover why setting automated stop-loss orders on a multi-million dollar portfolio acts like an unwarranted ejection seat during routine market turbulence, and learn structural risk management strategies that protect your cash flow. Plus, get an insider’s look at the NASA Roman Space Telescope’s thrilling “first light” image and discover what a blurry cosmic picture teaches us about fine-tuning your financial trajectory.
Retirement Big Picture
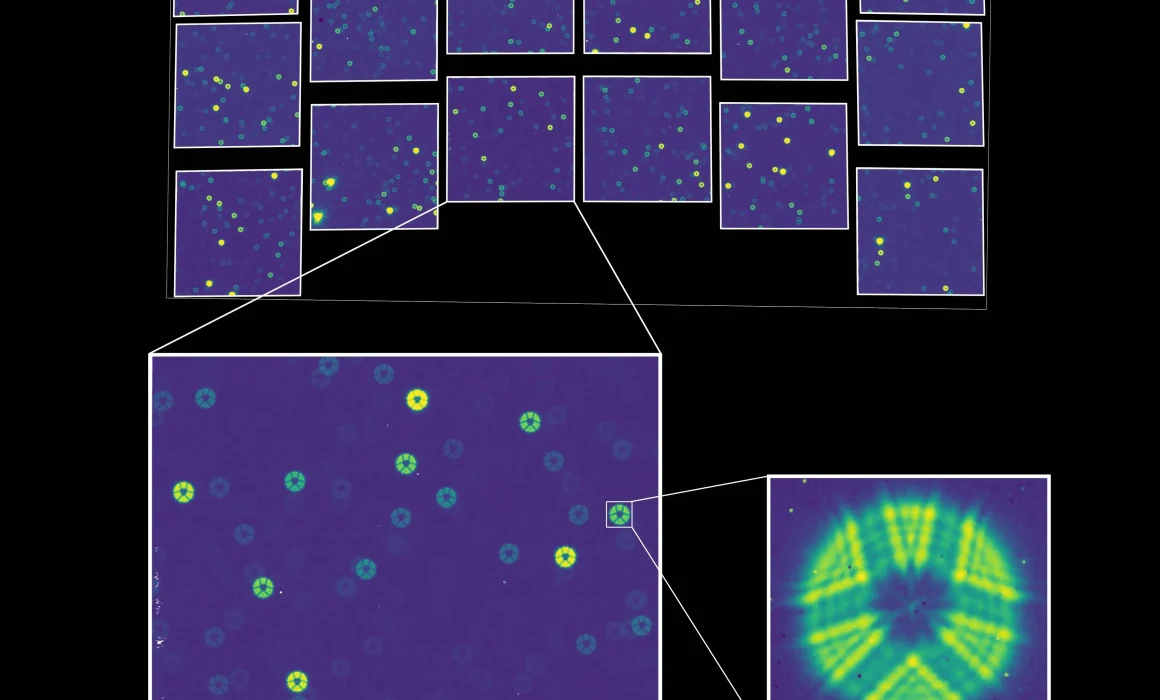
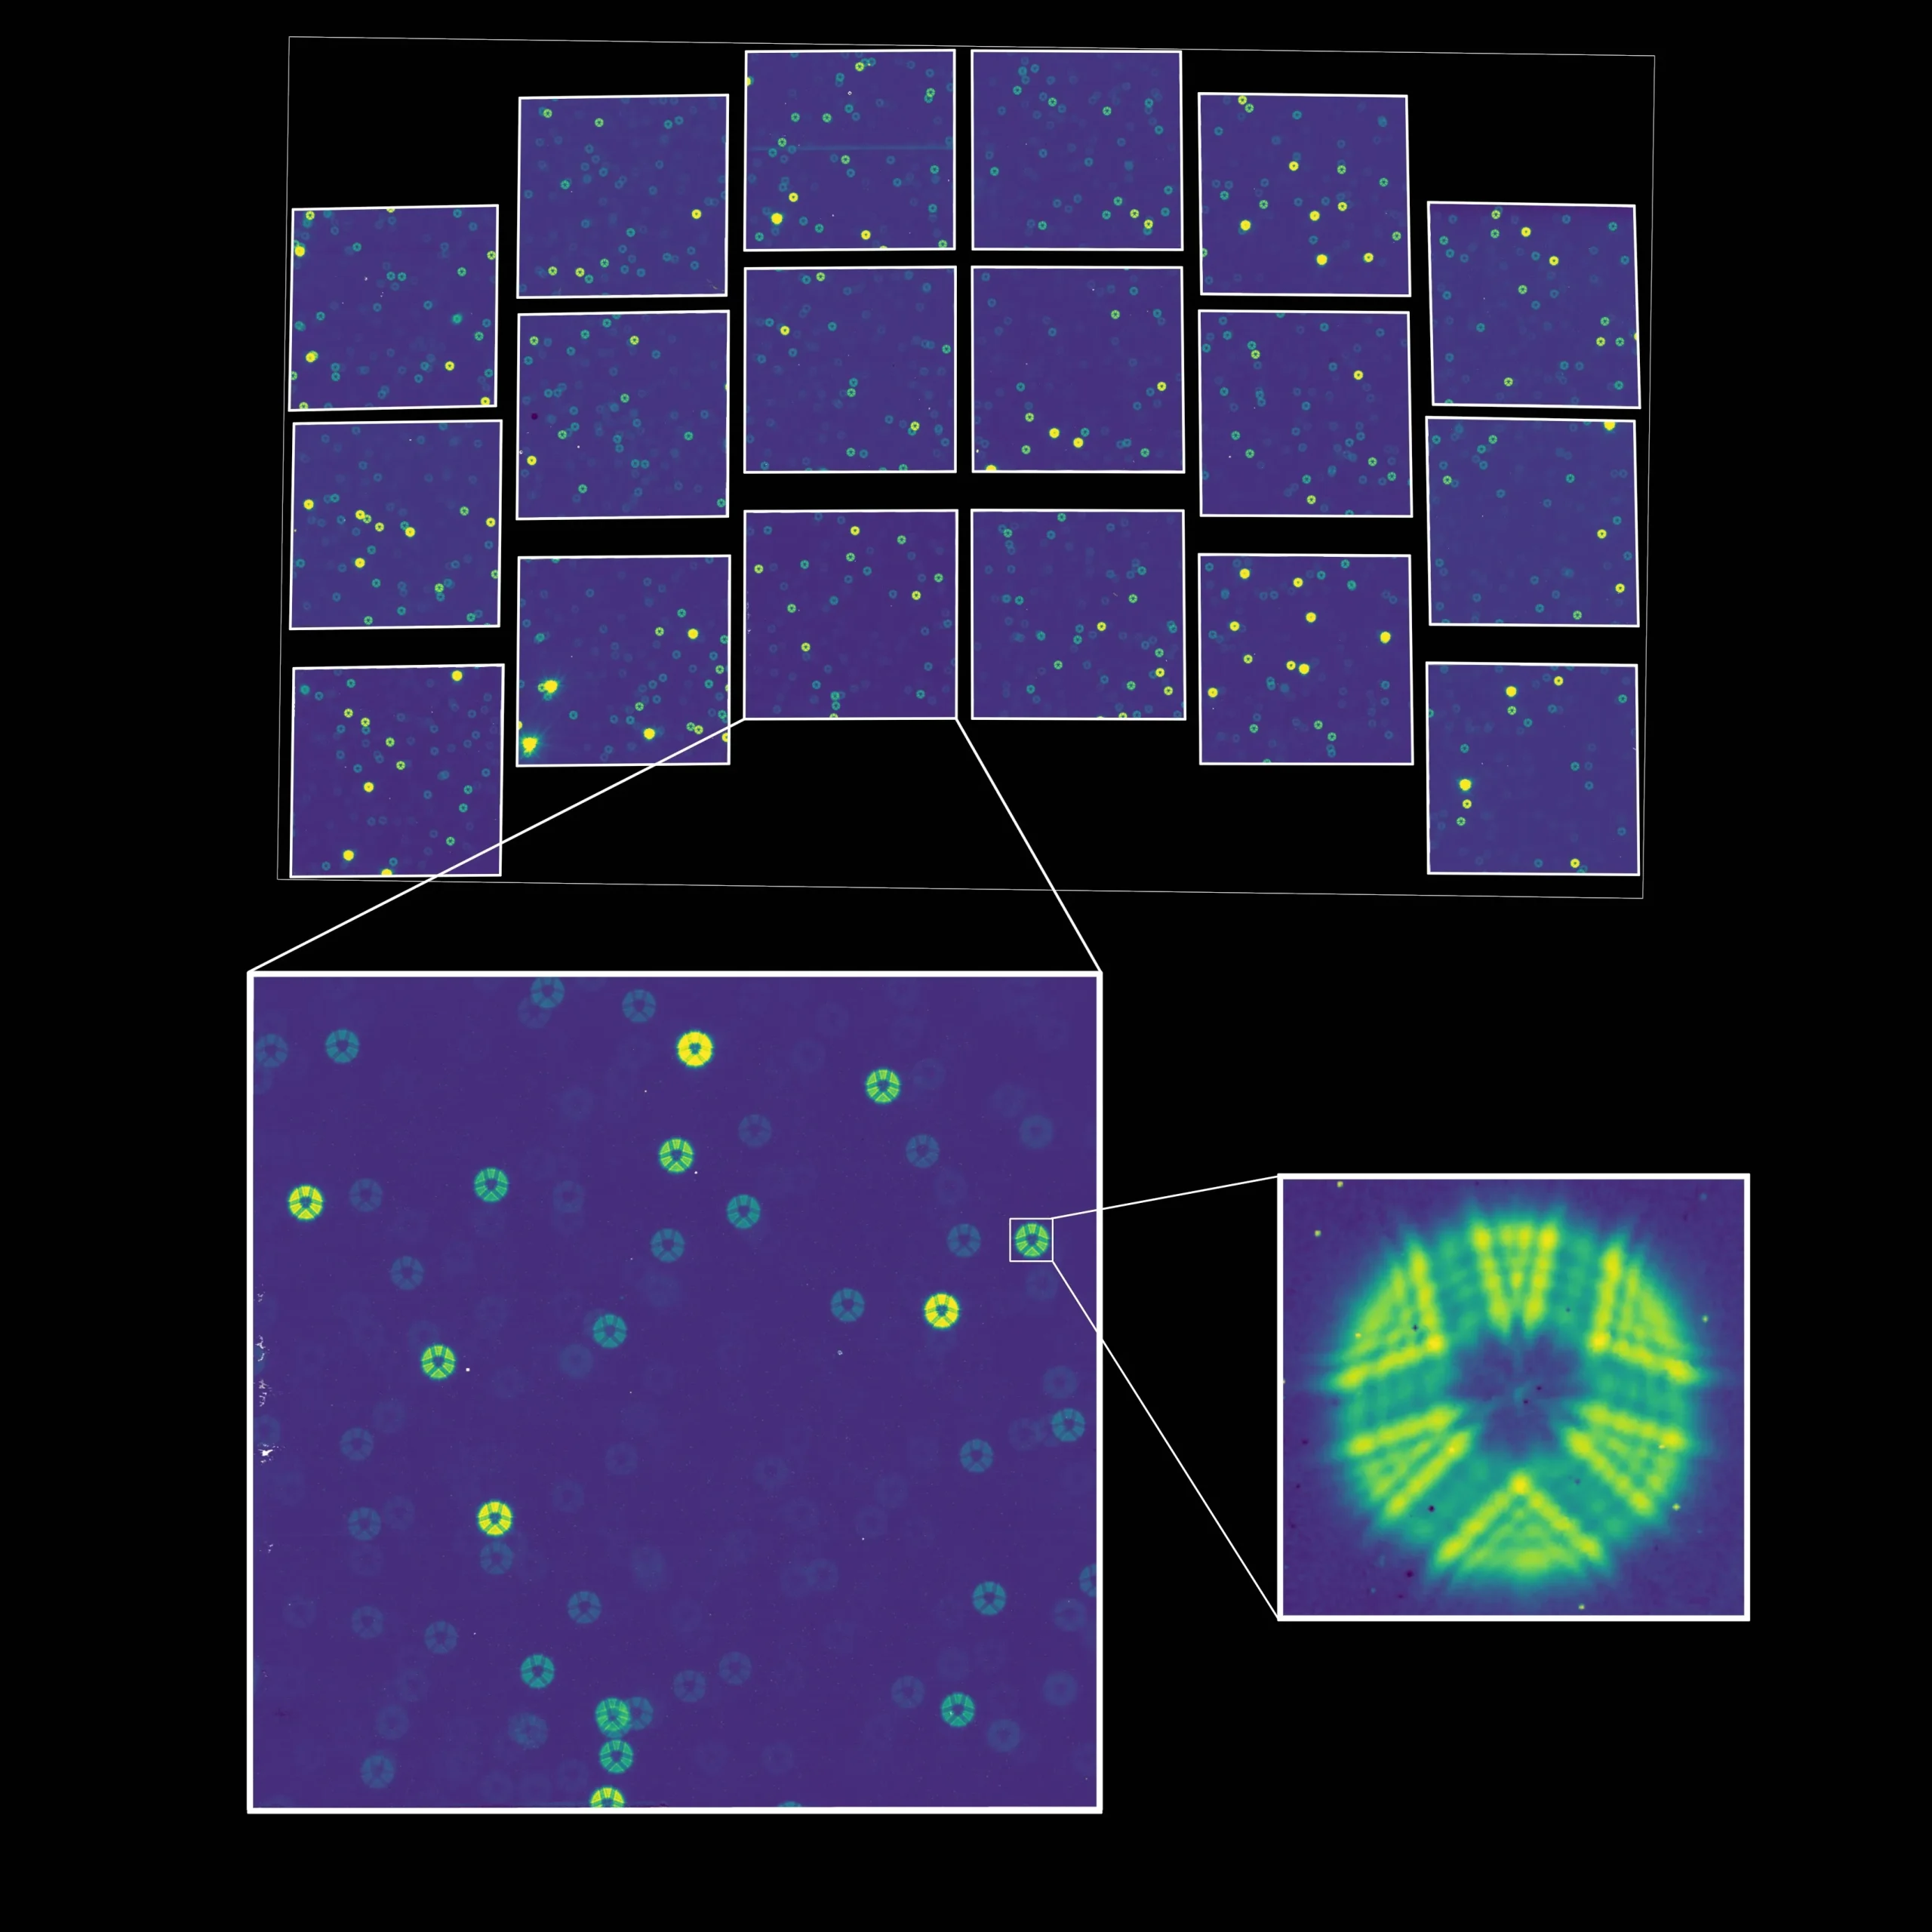
We highlight the September 17th release of the NASA Nancy Grace Roman Space Telescope’s “first light” image, captured by its 300-megapixel Wide-Field Instrument as the spacecraft cruises to the Earth-Sun L2 point. Though the initial public image shows stars that appear fuzzy, out of focus, and stretched into odd geometric shapes, astronomers are thrilled because this optical fingerprint—known as the point spread function—is expected prior to mirror alignment. Over the coming weeks, internal focusing mechanisms will adjust the mirrors microstep by microstep, transforming these initial broad, unpolished cosmic views into crisp, sharp, brilliant images of the universe.
Image Credit: NASA
Sign Up for The Launch
The Launch is a weekly email from Dr. Chris and his team. It’s full of retirement tips, news, listener questions & more, straight from us to your inbox. Get smarter about retirement in just 5 minutes every week. Let’s go!
Episode Resources
Episode Transcript
Introduction
Dr. Chris Mullis, PhD, CFP®: When NASA adjusts a spacecraft’s thrusters by just a fraction of a degree, it isn’t aborting the mission, it’s staying on course. So why does a minor quarter point interest rate change from the Federal Reserve make so many people feel like their financial trajectory is in a tailspin?
Today, we’re analyzing what the Fed rate hike means for folks headed for or already in retirement. Are you ready?
NASA: 3, 2, 1, 0 and lift off. Lift fell Americans return to space as discovery clears the tower.
Dr. Chris Mullis, PhD, CFP®: Welcome back to Retirement Isn’t Rocket Science. This is episode 27, and it is a very special one. Not only is this the kickoff of season two, but today marks our official first anniversary. Before we dive into today’s topic, I wanted to take a moment to say a huge thank you to every single one of you.
Your encouragement, support, reviews, and messages over the past year have meant the world to me. Thank you for being on this ride with us and making our first year so incredible. I’m your host, Dr. Chris Mullis. I used to build maps of the universe using NASA’s space telescopes. Today, I build retirement roadmaps for people like you.
As a certified financial planner with 21 years of experience, I’m here to help you lower your taxes, strengthen your portfolio, and give you the confidence and the capacity to spend more. Regardless of where you’re listening or watching, be it on Apple Podcasts, Spotify, YouTube, or your favorite app, don’t forget to subscribe or follow so you don’t miss a single show.
And please share the podcast with a friend or family member who you think could benefit from it. Help us grow our audience as we head into year two. Together, let’s fuel, guide, and educate as many people as possible to successfully launch into the greatest chapter of life, retirement
In today’s show, is the Federal Reserve’s latest rate hike a launchpad or a cash trap for your retirement? Why stop loss orders are the wrong guardrail for a multi-million dollar retirement portfolio and what to use instead. And first light for the NASA Roman Space Telescope. Why a blurry picture is thrilling news for the future of astronomy
Retirement Briefing Room
Dr. Chris Mullis, PhD, CFP®: Welcome to the Retirement Briefing Room. This is where we break down key financial moves, spotlight proven wins, and build a mission plan that puts your retirement on autopilot. If you tuned into the financial news on September 16th, you probably saw bold red tickers proclaiming that the Federal Reserve raised its benchmark interest rate by a quarter percentage point, bringing its target range to three point seven five to four percent.
This marks the central bank’s first rate increase in three years, aimed squarely at cooling off stubborn inflation that sat at three point four percent
year over year in August. Now, if you’re sitting on a multi-million dollar nest egg, news like this can easily sound like an alarm bell ringing in the spacecraft cabin. The financial media loves to treat every quarter point thruster burn as if it’s an imminent trajectory failure. But here’s the secret that every rocket scientist and seasoned certified financial planner knows: minor atmospheric shifts require calm navigation and precise instruments, not emotional emergency maneuvers. To help us understand what this interest rate adjustment actually means for your investment portfolio, your tax management, and your cash flow strategy, we are examining Cameron Huddleston’s recent AARP article titled “What the Fed’s Rate Hike Means for Retirees,” and I’m going to share my experience and wisdom from the perspective of a retirement planner. Let’s look past the sensational headlines, cut through the financial jargon, and unpack how experienced financial advisors analyze this economic shift in the real world
First, let’s address the psychological impact of headline news. When the Federal Reserve adjusts rates, financial headlines immediately start broadcasting predictions about market volatility, falling bond values, and changing borrowing costs. It is completely natural for diligent savers to feel a sudden urge to do something with their hard-earned money.
However, I frequently emphasize to our clients, mainstream financial media is engineered to amplify macroeconomic events into high-stakes drama. A quarter-point rate adjustment is a minor detail in a multi-decade retirement horizon. Attempting to overhaul your portfolio or timing the market in response to Federal Reserve announcements is a classic rookie mistake that usually results in unnecessary tax consequences and missed growth opportunities.
Public policy professor Christian Weller points out in the AARP piece that the single best advice for investors in times of headline uncertainty is simply to stay the course. I strongly endorse this exact perspective. I caution retirees against making knee-jerk adjustments to their asset allocation based on short-term economic news or Federal Reserve decisions.
A comprehensive, professionally designed retirement plan is built with the explicit expectation that interest rate cycles, inflation fluctuations, and market pullbacks will happen. You don’t redesign the spacecraft mid-flight just because you encountered a brief pocket of atmospheric turbulence
Second, let’s examine what this rate hike means for short-term cash reserves and liquidity planning. Higher benchmark rates prompt financial institutions to offer increased interest rates on deposit accounts. Retirees holding cash sitting in savings accounts, money market funds, or short-term certificates of deposit will see their yields edge higher, helping those dollars better keep pace with inflation.
Consumer analyst Ted Rosman highlights that this is a genuine silver lining for savers. From an actionable financial planning perspective, top advisors utilize structured cash buffer frameworks to manage this exact space. For example, my firm employs a framework we call the war chest or your retirement runway, where retirees maintain approximately three to five years of portfolio withdrawal needs in stable liquid assets like cash, money market accounts or bonds.
When the Fed raises rates, these cash buffers earn a healthier yield, strengthening the defensive shield that funds your daily living expenses without forcing you to liquidate stocks during market pullbacks. However, there is a subtle trap hidden here that every retiree with a significant nest egg must avoid.
That’s the high-yield cash trap. I caution retirees against becoming overly comfortable sitting on cash just because yields on money market accounts look attractive at four or five percent. While earning nominal yields on cash is a welcome bonus, holding excessive cash, I call this lazy money, holding this as a long-term investment strategy is very dangerous.
When you factor in federal and state income taxes on interest income, which is taxed at your highest ordinary income tax rate, alongside persistent real inflation, cash instruments rarely preserve real purchasing power over a twenty or thirty-year retirement. Cash is essential for short-term liquidity, but relying on it for long-term growth will cause your wealth trajectory to lose velocity over time.
Third, let me translate what this means for long-term portfolio growth, bonds, and your inflation defense strategy. In the AARP article, Boston College researcher Laura Quinby notes that the impact of a rate hike depends heavily on how a household is invested and their specific income sources.
, And let me build on this concept by reminding us to distinguish between headline consumer price index figures and your personal inflation rate. Headline CPI measures a broad, generic national basket of goods. Your personal inflation rate, however, depends entirely on your personal spending habits, healthcare costs, travel frequency, and how much of your retirement income automatically adjusts for inflation through Social Security or inflation-indexed pensions.
To shield your purchasing power against long-term inflation gravity, you must maintain exposure to growth assets. Equities remain the primary engine for long-term purchasing power preservation. Fleeing equities out of market anxiety or settling for safe cash yields leaves your retirement vulnerable to compounding inflation over a multi-decade horizon.
What about the bond side of your portfolio? The AARP article correctly notes that when interest rates rise, bond prices temporarily fall, which can cause the value of a bond-heavy portfolio to dip on paper. But let me clarify: short and intermediate-term bonds are not in your portfolio to generate aggressive capital gains.
Their primary mission is to provide portfolio stability, act as a buffer during stock market downturns, and generate reliable income. Furthermore, as existing short-term bonds mature, bond fund managers reinvest those principal dollars into new bonds offering these higher yields, ultimately boosting your portfolio’s income-generating power over time.
Fourth, let’s look at the borrowing side of the equation and cash flow protection. The article highlights that while thirty-year fixed rate mortgages are largely insulated from direct Fed rate moves, variable rate debt, such as credit cards and home equity lines of credit, see rate hikes pass through automatically within a month or two.
I would emphasize that carrying variable rate debt into retirement introduces unpredictable expenses that erode fixed cash flows. Rising interest rates mean your borrowing costs increase automatically, creating unnecessary drag on your monthly budget. I, and I think most other financial planners, strongly advise eliminating variable rate debt prior to retirement or locking in fixed rates to protect your cash flow from Federal Reserve policy shifts. Additionally, instead of making radical changes to your asset allocation when economic conditions shift, I recommend adopting dynamic spending guardrails, such as the Guyton-Klinger framework. Rather than sticking rigidly to a static withdrawal rate, dynamic guardrails allow you to adjust your portfolio distributions up or down within safe parameters based on real-world market returns and inflation. This flexibility allows retirees to absorb economic shifts comfortably without risking portfolio longevity or panicking over news headlines.
Before we conclude today’s briefing room analysis, let’s summarize the key mission points every diligent saver should keep in mind. First, treat Federal Reserve rate hikes as headline noise rather than a signal to overhaul your long-term investment strategy. Second, optimize your cash buffer in competitive money market accounts, but avoid the cash trap by keeping your long-term growth assets invested in equities to outpace inflation. Third, reframe the role of your bonds as your portfolio stabilizers and recognize that higher interest rates enable bond funds to reinvest at higher yields over time.
Fourth, eliminate variable rate debt like HELOCs and credit cards before entering retirement to protect your monthly cash flow and utilize dynamic spending guardrails to navigate inflation changes smoothly. Economic policy will always shift, and interest rate headlines will always generate noise.
But when you build a retirement plan grounded in a structured liquidity buffer, disciplined equity growth, and tax-efficient cash flow, you don’t need to fear the Federal Reserve. Your financial flight plan remains smooth, steady, and securely on target . You’ll find a link to the AARP article in today’s show notes and in our weekly newsletter. Now, let’s head over to Mission Control to answer your financial questions and get you retirement ready
Ask Mission Control
Dr. Chris Mullis, PhD, CFP®: Discovery Houston, 20 seconds to LOS. Tres Hothead. Nice to be in orbit.
Welcome to Ask Mission Control. This week’s question comes from Dan. Dan writes, “I’m turning 70 next month. Although I remain full-time, I’m starting to think about retirement. My question is, should I start using stop losses in my investment account? For example, my portfolio balance is currently just north of two million dollars.
Putting a stop loss at one point nine million would limit the account loss should there be any major correction in the market.” Dan , First off, happy early 70th birthday. Reaching a two million dollar nest egg while continuing to work full-time is a fantastic achievement. It reflects decades of hard work, discipline, and diligent savings.
It’s completely natural that as you stand on the launch pad of retirement, you want to protect what you built. Wanting a safety floor at one point nine million dollars comes from a good place. However, in financial planning, placing automated stop-loss orders on a long-term retirement portfolio is like installing an automated ejection seat on a spacecraft during routine atmospheric turbulence. The rocket hits a minor bump at fifty thousand feet, the automated system panics and fires the ejection seat, leaving you parachuting into the ocean while the ship stabilizes and flies right into orbit without you.
Let’s unpack why a stop-loss order sounds reassuring on paper, but frequently backfires for long-term retirement planning. First is execution and market gap risk. Setting a stop loss at one point nine million does not guarantee you sell at one point nine million. When market volatility pushes prices down to your stop price, your instructions instantly convert into a market order.
If negative news breaks overnight or over the weekend or panic hits at the opening bell, market prices can gap down well below your target floor. Instead of exiting at one point nine million, your trade might execute at one point six million or even lower. You haven’t secured a safety floor, you’ve triggered an automatic fire sale. Second is getting whipsawed. Financial markets fluctuate naturally. A standard five percent to eight percent market dip, that’s a normal occurrence on a healthy market cycle. In fact, the average intra-year drawdown for the US market is fifteen percent.
So these natural fluctuations can easily trigger your stop loss, liquidating your investments into cash near the bottom. To make this strategy work, you have to be right twice, knowing when to sell and knowing precisely when to buy back in. Most investors forced into cash during a dip sit on the sidelines out of fear, completely missing the inevitable recovery that usually hits much faster than the fade down.
That turns a temporary paper loss into a permanent unrecoverable setback Third, consider taxes and trajectory. Since you’re working full-time at age seventy, you are likely in a higher tax bracket. Triggering a mass sale in a taxable account creates an unnecessary tax bill today.
Even if funds are sitting in an IRA, dumping equities strips your portfolio of the growth engine needed to outpace inflation during retirement. So how do you protect your multi-million dollar portfolio without using risky stop loss orders? Instead of automating exit triggers, a certified financial planner uses structured risk management.
Specifically, that means proper asset allocation and a dedicated cash flow cushion. This is where that war chest or retirement runway framework comes in. By keeping multiple years of expected retirement income in safe, non-volatile assets like short-term treasuries, money market funds, or cash accounts, you construct a secure launchpad cushion.
When the market hits a storm, I didn’t say if, I said when, because we do know storms come, they’re absolutely normal. When the market hits a storm, your day-to-day lifestyle is completely protected. You never have to sell equities while prices are down, giving your growth investments time to recover. So Dan , here are those key points one last time.
Number one, stop loss orders do not guarantee execution prices during market gaps and can sell assets far below your target floor. Number two, automated stops turn temporary market fluctuations into permanent realized losses, requiring you to time the market twice. And third, structural risk management like asset allocation and a multi-year cash cushion protects your retirement income while maintaining growth.
Dan, collaborating with a retirement planner to set up this multi-bucket strategy will likely provide you true peace of mind without leaving your launch strategy at risk to a potentially faulty mechanical trading system.
Remember, true market protection doesn’t come from pushing the panic button when the market gets bumpy. It comes from building a trajectory that can handle that turbulence and keep you comfortably in orbit. If you’ve got a retirement question that you’d like us to answer on the show, head over to Retirement Isn’t Rocket Science dot com and click ask a question.
Or even better, you can skip to the front of the line by calling Mission Control at seven zero four two three four six five five zero and record your audio question. Now, let’s take a close look at the very first light received by the Roman Space Telescope, the very first image of many hundreds of thousands to come
NASA: In Discovery Houston, we’ve got a good picture of Steve.
Retirement Big Picture
Dr. Chris Mullis, PhD, CFP®: Welcome to the retirement big picture part of our show. This is where we look up and look out to expand our appreciation and understanding of the amazing universe. And this doesn’t have to happen with a NASA space telescope.
Just this morning, I was sipping a cup of coffee in the pre-dawn and looked up and enjoyed my first early fall view of the Orion constellation, along with the asterism, the Pleiades, and a beautiful view of Taurus. So wherever you are, look up and enjoy the sky above today, we’re talking about a monumental milestone in space exploration that happened just a few days ago on September 17th. NASA officially released the very first image, what we in the astrophysics world call first light.
That is the first light, the very first image from the brand-new Nancy Grace Roman Space Telescope. Now, Roman launched August 30th of this year and is currently cruising out to its permanent operational home. That’s a special gravitationally balanced spot in space called the Earth-Sun L2 point, about one million miles away.
This is where the gravitational pull of the Earth and the sun balance out nicely that keep spacecraft steady in orbit. It takes about a month to travel out there, but the engineering team certainly hasn’t been napping on the journey. While en route, engineers have been busy prepping its primary workhorse instrument, the wide-field instrument, WIFI, and letting it cool down.
Cooling those camera detectors down to super cold temperatures is crucial because WIFI observes invisible and near-infrared light, and ambient heat creates unwanted background noise in sensitive infrared detectors. So what exactly is first light? It’s that exhilarating moment when a telescope opens its eyes for the very first time, points at an astronomical target, and lets real cosmic photons hit its detectors.
For the scientists and engineers who spent years designing and building these complex space instruments, first light is a nerve-wracking, hold-your-breath moment. When NASA released Roman’s first image, the initial reaction from the general public was a bit mixed because frankly, the picture looks a little strange.
The stars look out of focus, fuzzy and stretched in weird geometric shapes. But if you ask an astronomer or a rocket scientist, we are practically jumping for joy. Why? Because it’s supposed to look like that right now. You see, the wide-field instrument is an absolute technological marvel. It houses 18 individual high-tech detectors totaling roughly 300 megapixels.
To put that into perspective, Roman’s view of the sky is about 100 times larger than the Hubble Space Telescope’s field of view. While Hubble gives us exquisite, ultra-deep pinpoint views in space, Roman is custom-built to survey vast swaths of the cosmos at once.
When a space telescope first turns on, the mirrors aren’t fine-tuned or aligned yet. That fuzzy shape around each star is called the point spread function, or PSF. It’s the optical fingerprint created when starlight passes through the telescope’s internal frame and mirrors while out of focus.
Over the coming weeks, engineers will use internal focusing mechanisms to move the mirrors microstep by microstep until those fuzzy stars sharpen into crisp, brilliant points of light. We’ve seen this exact process before. Back when the James Webb Space Telescope took its first light pictures, the stars looked like a scattered cluster of double images before optical alignment.
And way back in 2003, when the Spitzer Space Telescope sent back its first light images, astronomers were startled to see stars shaped like tiny triangles. Yet, once focused, Spitzer went on to revolutionize our understanding of star formation and exoplanets for 16 years. Roman’s wide-field lens will soon deliver unprecedented cosmic surveys.
It will work hand-in-hand with other legendary observatories, combining its wide infrared views with JWST’s deep infrared power and the high-energy X-ray vision of the Chandra X-ray Observatory. When you layer Chandra’s view of superheated gas with JWST’s infrared clarity, you unlock details about grand cosmic structures that no single telescope can reveal alone. It’s a wonderful reminder every grand voyage starts with a broad, slightly unpolished view before everything gets dialed in and fine-tuned into a sharp, brilliant focus.
You’ll find the Nancy Grace Roman Space Telescope’s first light image in this week’s newsletter called The Launch. You can sign up for The Launch at retirementisntrocketscience.com.
Conclusion & Action Items
Dr. Chris Mullis, PhD, CFP®: And that’s a wrap for today’s show. Look, whenever the Federal Reserve starts tweaking interest rates, the financial media loves to make it sound like you need an advanced degree in astrophysics just to protect your nest egg. But as we always say around here, retirement isn’t rocket science.
You don’t need to predict where the macro economy is heading. You just need to run your own playbook. Before we log off, let’s nail down your three mission-critical action items. Number one, audit and shop your cash reserves.
Don’t let your short-term cash sleep on the job. Check where your liquid savings are sitting right now. That one to three year spending buffer should be working for you in competitive high yield money market funds or short-term treasuries pulling in solid yield. Just remember the flip side, don’t hoard too much cash.
Anything beyond your buffer belongs right back in your long-term growth bucket so it can keep building wealth. Number two, slam the door on variable rate debt. When the Fed raises rates, variable debt gets real expensive, real fast. Sweep your accounts for any sneaky credit card balances or home equity lines of credit.
Make it a priority to pay down those aggressively or lock them into fixed rates now so rising interest charges don’t take a bite out of your monthly living budget. And number three, calculate your personal inflation rate. Turn off the panic on cable news and ignore those generic national CPI headline numbers.
What actually matters is your household budget. Map out the real world expenses against your inflation indexed income sources like Social Security. Once you know your personal number, you can make sure your stock allocation is properly tuned to defend your true purchasing power for the long haul.
At the end of the day, central bankers are going to do what central bankers do, but you hold the controls to your own financial launchpad.
This is Dr. Chris reminding you that you are both the commander and the pilot of your retirement mission.
Take control of your trajectory today to worry less and retire more, because with smart planning, retirement isn’t rocket science
Credits
Dr. Chris Mullis, PhD, CFP®: We thank the National Aeronautics and Space Administration for providing the radio communications between the space shuttle astronauts and the flight controllers.
Disclaimer
This show is for informational and entertainment purposes only. It is not specific tax, legal, or investment advice. Before considering acting on anything you hear in this show, first consult your own tax, legal, or financial advisor